Audit Season Stress: Why High-Touch Fund Administration Matters
The vital role of attentive fund administration services in minimizing stress, addressing auditor inquiries, and safeguarding operational efficiency during audit season.
For asset managers, audit season is more than a routine compliance exercise—it is a critical period where operational precision, regulatory adherence, and investor transparency are all under the microscope. Even well-run funds can feel pressure during this time: schedules tighten, audit teams request detailed reconciliations, and reporting must be flawless across multiple fund structures and geographies.
For managers working with fund administrators who take a tech-first, low-touch approach, these challenges are magnified. While technology can streamline reporting and data aggregation, it cannot on its own replace proactive, hands-on guidance. Additionally, administrators with low or varying service quality may struggle to scale up or adapt to clients’ changing needs, further complicating the audit process.
The most common stress points exacerbated by a lack of high-touch support include:
Delayed responses to audit inquiries: Solely tech-driven platforms often prioritize automated workflows over real-time human support. When auditors raise questions—whether about NAV adjustments, intercompany transactions, or fee calculations—delays in response can cascade into last-minute escalations.
Limited visibility into complex structures: Private funds often have multi-class shares, co-invest vehicles, or feeder funds spanning multiple jurisdictions. Without a dedicated team that understands these nuances, managers risk receiving incomplete or confusing reports, increasing the potential for audit findings or rework.
Incomplete reconciliations: Automated reporting can handle standard positions and cash flows, but unusual transactions—such as NAV loans, secondary trades, or FX adjustments—require expert judgment. Low-touch models can miss these, leaving managers responsible for manual corrections under tight deadlines.
Reactive problem-solving: Tech-first providers often wait for issues to surface before addressing them. In contrast, high-touch administrators anticipate anomalies—spotting missing documents, reconciling prior period adjustments, and preparing schedules proactively to minimize disruption.
Pressure on internal teams: When administrators are unavailable or lack deep operational knowledge, fund teams must shoulder the burden—preparing reconciliations, chasing auditors, and addressing exceptions—diverting time from strategy and investor engagement.
Managing risk
A high-touch fund administration model mitigates these risks. Dedicated teams with deep operational knowledge and experience across fund structures:
Serve as a single point of contact for audit and regulatory queries, ensuring timely, accurate responses.
Prepare detailed pre-audit schedules, including cash reconciliations, capital call and distribution statements, and third-party confirmations, as an integral part of our service delivery—without additional costs or requests. This high-touch service is embedded directly into our offering, ensuring that clients receive the support they need without added stress.
Coordinate across custodians, prime brokers, and portfolio managers to reconcile positions and verify valuations.
Anticipate unusual or complex items, such as subscription line loans, multi-jurisdictional tax considerations, or NAV adjustments for illiquid assets, reducing last-minute surprises.
Provide transparent, customizable reporting tailored to the needs of auditors, investors, and internal management.
Ultimately, the difference between a stressful audit and a smoothly managed one comes down to the support model. Technology is essential, but human expertise, proactive guidance, and a relationship-driven approach ensure accuracy, efficiency, and peace of mind.
At Alter Domus, we combine leading-edge operational platforms with white-glove service. By integrating technology with hands-on support, we help asset managers navigate audit season confidently reducing risk, freeing internal resources, and delivering the reliability that investors and auditors demand.
Explore how tech is reshaping fund administration through automation, APIs, and smart ops. Discover what GPs and COOs should prioritize in 2025.
The investment landscape has shifted dramatically, with fund administrators facing rising investor expectations, regulatory complexity, and market volatility. Traditional approaches no longer suffice.
Investors now demand greater transparency, faster reporting, stronger security, and lower fees—making technology the key differentiator between administrators that thrive and those that fall behind.
Most wealth managers already rely on digital platforms—94% of firms with $500M+ in assets and 61% of smaller firms use fintech to improve client engagement and efficiency.1 The question is no longer whether to adopt new technology, but how quickly and effectively it can be deployed to transform operations.
How Technology Is Transforming Fund Administration
From spreadsheets to smart systems
The journey from manual processes to intelligent automation represents perhaps the most significant shift in fund administration technology. Historically, fund administrators relied heavily on spreadsheets and manual data entry—approaches that were not only time-consuming but prone to human error.
Modern fund administration technology has evolved to replace these outdated methods with integrated systems that automate routine tasks. Advanced platforms now handle everything from NAV calculations to investor communications with minimal human intervention. This transition eliminates the bottlenecks associated with manual processing while dramatically reducing error rates and improving overall efficiency.
Digitization of workflows and document handling
Document management has traditionally been one of the most labor-intensive aspects of fund administration. The digitization of workflows and document handling represents a quantum leap forward, enabling administrators to process, store, and retrieve critical information with unprecedented speed and accuracy.
The benefits extend beyond mere efficiency. Digital workflows create audit trails that enhance compliance and security while reducing the risk of document loss or unauthorized access. For fund managers and investors alike, this translates to greater confidence in the integrity of administrative processes.
Role of APIs in real-time data sharing
Application Programming Interfaces (APIs) have revolutionized how fund administration systems interact with each other and with external platforms. By enabling seamless data exchange between previously siloed systems, APIs create a connected ecosystem that supports real-time information sharing and processing.
This connectivity allows fund administrators to integrate with banking platforms, trading systems, and investor portals, creating a unified experience for all stakeholders. Rather than waiting for batch processing or manual reconciliations, information flows continuously between systems, enabling near-instantaneous updates and reporting.
Benefits for GPs and Operations Teams
The power of RNFs becomes clear when comparing SCR requirements. Consider two scenarios:
Faster, more accurate investor reporting
Perhaps the most tangible benefit of fund administration technology is the transformation of investor reporting. Traditional reporting cycles often stretched over weeks, with manual data collection and verification creating significant delays. Today’s technology-enabled administrators can compress these timelines dramatically, delivering accurate reports in days or even hours. 81% of clients using fintech platforms in 2025 report higher satisfaction from greater transparency and easier access to investment data.1
This acceleration doesn’t come at the expense of quality. In fact, automated data processing and validation actually enhance accuracy by eliminating human errors and ensuring consistent application of accounting principles. Whether you’re a venture capital fund administration or managing traditional vehicles, digital tools compress reporting cycles from weeks to hours.
Improved scalability for fund growth
Traditional fund administration models faced inherent limitations when it came to scaling operations. Adding new funds or investors typically requires proportional increases in staffing and resources, creating operational challenges and cost pressures during periods of growth.
Modern fund administration technology breaks this linear relationship between growth and resource requirements. Cloud-based fund administration services can scale elastically as you grow—from managing a single fund in-house to migrating fund admin activities to a third-party platform. This enables administrators to support fund managers through growth phases without service disruptions or quality compromises.
Better risk management and compliance readiness
The regulatory landscape for investment funds continues to grow more complex, with new requirements emerging across jurisdictions. Fund administration technology has evolved to address this challenge through automated compliance monitoring and regulatory reporting capabilities.
Advanced systems now use regulatory rules engines to continuously monitor transactions and positions, flagging potential compliance issues early for proactive remediation. This reduces risk and workload for operations teams, replacing manual tracking and sampling with automated, comprehensive monitoring.
Comparing Traditional vs. Tech-Enabled Models
Manual bottlenecks vs. automated efficiency
The contrast between traditional and technology-enabled fund administration is clearest in operational bottlenecks. In conventional models, tasks like month-end reconciliations, NAV calculations, and investor distributions often create backlogs demanding all-hands-on-deck efforts.
Tech-enabled administrators remove these bottlenecks through automation. Reconciliations that once took days now finish in hours or minutes, with only exceptions flagged for review. NAV runs on set schedules with little manual input, and distributions flow through straight-through processes.
This shift goes beyond speed—it reshapes fund administration. Instead of routine data processing, teams now focus on exception handling, client relationships, and value-added analysis.
Fragmented systems vs. integrated platforms
Traditional fund administration relied on separate systems for accounting, investor services, compliance, and reporting, leading to integration issues, data inconsistencies, and poor user experiences.
Modern platforms take an integrated approach, spanning all functions to ensure data consistency, streamline workflows, and deliver a cohesive experience. With all data stored in a single ecosystem, administrators can produce comprehensive reports and analytics without the transformation challenges of fragmented systems.
What to Look for in a Technology-Forward Partner
Infrastructure maturity, flexibility, and security
When selecting a fund administrator, prioritize technology infrastructure. Leading partners invest in enterprise-grade platforms that combine reliability, flexibility, and strong security.
Mature infrastructure ensures uptime, processing power, disaster recovery, and robust change management to prevent disruptions. Flexible platforms support diverse fund types, complex structures, and a wide range of asset classes, including alternatives.
Security is critical amid rising cyber threats. Top administrators deploy encryption, multi-factor authentication, access controls, and continuous monitoring, while maintaining SOC 2 and ISO 27001 compliance.
Ability to scale with complex fund structures
As investment strategies grow more sophisticated, fund structures have become increasingly complex. When considering In-house vs third-party fund administration, look for providers whose platforms already support complex structures like master-feeder and venture capital fund administration.
These systems also scale to diverse investor needs, managing varied fee arrangements, tax treatments, reporting requirements, and side letters, ensuring all investor-specific provisions are accurately implemented and documented.
Conclusion
The technological revolution in fund administration represents both a challenge and an opportunity for investment managers. Those who partner with technology-forward administrators gain significant advantages in operational efficiency, investor satisfaction, and regulatory compliance.
As we look toward the future, tech like AI and machine learning will continue to enhance automation capabilities, while blockchain[1] and distributed ledger technologies may fundamentally transform transaction processing and verification. Data analytics will grow more sophisticated, providing deeper insights into portfolio performance and investor behavior.
For fund managers navigating this evolving landscape, the choice of a fund administration service provider has never been more consequential. By selecting providers with robust, flexible technology platforms and demonstrated commitment to innovation, they can ensure that their administrative capabilities remain aligned with their strategic ambitions—today and into the future.
Disclaimer: THIS MATERIAL IS PROVIDED FOR GENERAL INFORMATION ONLY, DOES NOT CONSTITUTE INVESTMENT ADVICE, AND PAST PERFORMANCE IS NOT INDICATIVE OF FUTURE RESULTS.
Evolving Operations: The Rise of
Co-Sourcing in Private Markets
Co-sourcing is increasingly being seen as a viable operational model by asset managers. In this article, we break down the fundamentals of co-sourcing, and outline the factors driving its adoption.
Staying in Control
How do private markets firms scale operations while maintaining control? It’s a challenge facing CFOs, COOs, and fund controllers as the industry grows in scale and sophistication.
Over the past decade, private capital has become a mainstream asset class, with managers handling larger, more complex portfolios across diverse jurisdictions. The introduction of new fund structures—like continuation vehicles and co-investments—has expanded the toolkit for general partners (GPs) but also intensified operational demands amid rising regulatory pressures and limited partner (LP) expectations.
Eight Drivers of Co-Sourcing In Private Markets
A 2024 Private Markets Insight Report by Allvue Systems reveals that 84% of private capital firms plan to re-evaluate their operating models within the next 12–18 months, with modular co-sourcing as a key focus. Similarly, 88% of managers at the Fund Operator Summit Europe are exploring outsourcing or co-sourcing in operational areas, particularly in reporting and support functions. Here, we explore the driving forces behind the growing adoption of co-sourcing.
1. Complexity outpaces legacy models
Firms manage more funds, across more jurisdictions, for increasingly diverse investors. Co-sourcing provides the flexibility and transparency needed to navigate this complexity.
2. Control without Overhead
Managers want to own their data, systems, and client relationships—without carrying the full operational load. Co-sourcing allows firms to retain oversight while shifting execution to trusted partners.
3. Scalable without compromise
As strategies multiply and reporting timelines tighten, operational needs fluctuate. Co-sourcing provides institutional-grade support that flexes with demand, without overcommitting to permanent hires.
4. Enhanced governance and risk management
Regulators demand clear accountability on vendor oversight and operational continuity. Co-sourcing provides transparency into workflows, responsibilities, and data flows, strengthening governance.
5. Rising regulatory burden
SEC Form PF updates, AIFMD filings, ESG disclosures, and tax transparency rules require greater frequency and granularity in reporting. Co-sourcing ensures consistency and accuracy across jurisdictions.
6. Growing LP expectations
Investors want richer insights into performance, fees, and portfolio exposures—delivered faster. Co-sourcing gives managers the back-office strength to meet these expectations while retaining control of the client narrative.
7. Data and platform ownership
Unlike traditional outsourcing, co-sourcing ensures managers keep ownership of their platforms and data, while partners integrate into existing systems to maintain continuity and reduce transition risks.
8. Talent scarcity
Specialist skills in fund operations—such as waterfall calculations or jurisdiction-specific compliance—remain hard to source. Between 2020 and 2022, the U.S. lost more than 300,000 accounting professionals. Co-sourcing provides immediate access to expertise without lengthy recruitment cycles.
Co-Sourcing Overview
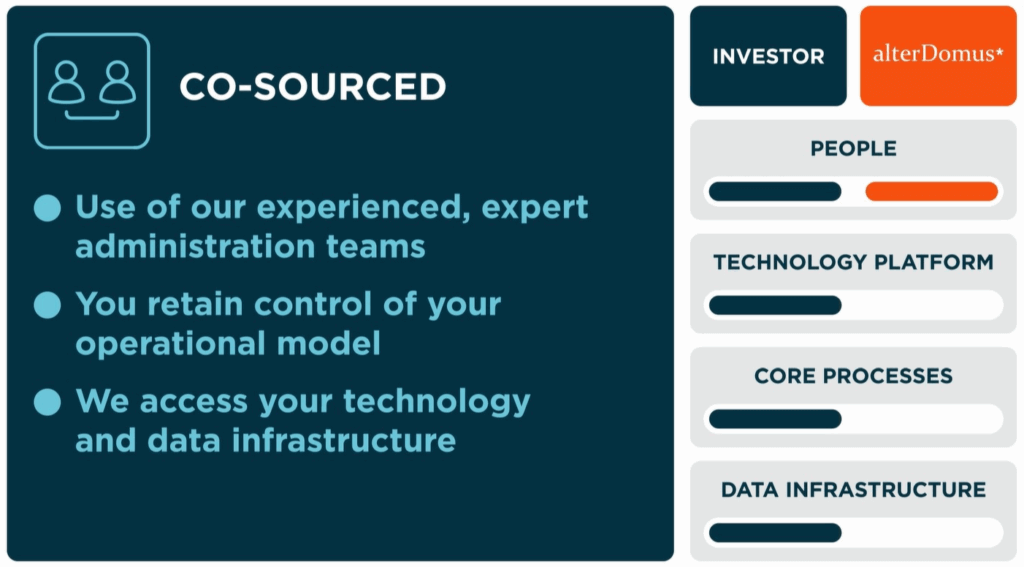
To address these challenges, many fund managers are shifting towards a hybrid co-sourcing approach, allowing them to retain control over their systems and client experience while leveraging specialist partners for precise execution.
Co-sourcing with Alter Domus offers General Partners a tailored approach that combines internal oversight with the executional strength of a specialist partner.
Our consultative model allows you to define the scope of support that best fits your unique operational needs, whether it’s fund accounting, capital activity, or regulatory reporting.
By maintaining system continuity and establishing strong governance, we empower your internal teams to focus on strategy while we handle execution efficiently.
Experience the benefits of enhanced operational resilience, regulatory readiness, and access to deep industry expertise.
Contact us today to explore how co-sourcing can elevate your business.
Co-Sourcing with Alter Domus:
A Custom Approach for
General Partners
Alter Domus understands that every General Partner has unique operational needs, which is why we offer tailored co-sourcing strategies to enhance efficiency and maintain control. Our expertise allows clients to focus on strategic growth while we manage execution and ensure regulatory compliance.
In the dynamic landscape of private markets, every General Partner (GP) has unique operational needs and preferences. At Alter Domus, we understand that a one-size-fits-all model simply doesn’t work. Instead, we adopt a consultative approach, collaborating with each client to define a co-sourcing strategy that aligns with their specific requirements.
Whether it’s supporting a single process like Form PF reporting or managing full fund accounting cycles within the client’s infrastructure, our flexibility ensures that we meet diverse operational contexts.
Here are some examples of how we empower GPs through customized services and expertise:
Typical Capabilities Include:
Fund Accounting: We prepare books and records using the client’s technology platform, with workflows designed for dual review and sign-off.
Capital Activity: We calculate and format capital calls, distributions, and notices, while clients retain approval rights and manage LP communications.
Regulatory Reporting: Our teams collect, map, and format data to comply with evolving requirements.
By partnering with us, internal GP teams can concentrate on oversight and strategy, while our dedicated professionals manage execution within a clearly defined control framework.
Making the Shift: Practical Considerations:
Transitioning to a co-sourcing model doesn’t mean overhauling existing systems or starting from scratch. With years of implementation experience, we guide clients through a structured transition focused on clarity, integration, and flexibility.
Through our extensive work with clients, we’ve identified three key building blocks essential for unlocking the full potential of a co-sourced operating model:
1. Define the right scope: We pinpoint operational areas under pressure, such as:
Fund closings and reconciliations
Capital statements and investor notices
Data preparation for regulatory reporting
Waterfall modeling and fee calculations
2. Maintain System Continuity: Clients keep their platforms while we securely integrate into their ecosystem, ensuring a single source of truth and avoiding fragmentation.
3. Establish Strong Governance: We align with each client’s compliance and oversight model, ensuring clear roles, documentation, and audit trails. Managers retain ultimate responsibility, while our teams execute defined workflows according to agreed service-level agreements (SLAs).
Figure 1 – The Benefits of Co-Sourcing with Alter Domus
Benefit
How it Helps
Internal Oversight
Control over systems, data, policies, and approval processes remains in-house
External Execution
Alter Domus executes defined tasks at scale, with speed, accuracy, and rigor
Data Ownership
Clients maintain full ownership of their infrastructure and data environment
Regulatory Readiness
Respond to changing rules with agile support and specialist knowledge.
Investor Responsiveness
Meet LP reporting demands faster and more consistently.
Operational Scalability
Expand or contract support without internal hiring constraints.
Access to Talent
Tap into deep experience across private equity, private credit, and real assets
Co-Sourcing: A Model for Long-Term Resilience
For private markets managers, operational resilience transcends mere business continuity; it’s about forging systems and partnerships that can adapt and thrive in an increasingly complex environment. Co-sourcing provides the perfect balance: the stability of internal oversight combined with the executional strength of a specialist partner.
At Alter Domus, we view co-sourcing as a strategic decision rather than just a service model. It empowers asset managers to focus on what truly matters: creating value for investors, meeting regulatory expectations, and growing with confidence.
If you’re reevaluating your operating model or exploring how co-sourcing could enhance your structure, we’re here to assist. Alter Domus has extensive experience supporting transitions of all sizes and complexities—whether you’re managing a single strategy or adding new strategies.
Our consultative model allows you to define the scope of support that best fits your unique operational needs, whether it’s fund accounting, capital activity, or regulatory reporting.
By maintaining system continuity and establishing strong governance, we empower your internal teams to focus on strategy while we handle execution efficiently.
Experience the benefits of enhanced operational resilience, regulatory readiness, and access to deep industry expertise.
Contact us today to explore how co-sourcing can elevate your business.
Looking to incorporate a Securitisation Vehicle? Here’s what you need to know
Securitisation vehicles are powerful tools that enhance liquidity, optimize risk management, and streamline capital structures. We explore how understanding their complexities can equip you to unlock financial opportunities and stay ahead in today’s evolving markets.
Securitisation has become an indispensable tool for institutions, asset managers, and asset owners. This sophisticated financial instrument offers a powerful trifecta: effective risk management, enhanced liquidity, and streamlined capital structures.
For those contemplating the incorporation of a securitisation vehicle, a comprehensive grasp of this intricate yet potentially lucrative process is crucial. By mastering its complexities, you’ll gain the confidence to navigate challenges adeptly and fully harness the myriad benefits securitisation offers, positioning yourself at the forefront of modern financial strategy.
What is Securitisation and why is important?
Securitisation is the process of pooling various types of financial assets, such as loans, mortgages, or receivables, and converting them into marketable securities. These securities are then sold to investors, allowing the originators to free up capital and manage risk more effectively. The cash flows generated from the underlying assets are used to pay interest and principal to the investors.
During 2017 and 2018, the European Union set up rules for securitisations. The goal was to bring the EU securitisation market back to life while also addressing worries about risky practices that had threatened stability after the global financial crisis of 2008. Since it entered into force in 2019-2020, the framework has strengthened investor protection, transparency, and financial stability.1
The European Commission has recently taken steps to revitalize the EU’s securitisation framework to make it simpler, more effective, and supportive of economic growth. These initiatives are part of the savings and investments union strategy, which focuses on improving the way the EU financial system works to boost investment and economic growth across Europe.
Benefits of Securitisation
Enhanced Liquidity
By converting illiquid assets into tradable securities, institutions and originators can access capital markets and improve their liquidity position. This transformation allows entities to free up resources that can be used for further lending to EU citizens and enterprises.
Risk Management
Securitisation allows for the transfer of risk from the originator to investors, which can help in managing credit risk and regulatory capital requirements. The main goal is to enable banks and other financial institutions to use the loans and debts they grant or hold, pool them together, and turn them into different types of securities that investors can purchase.
Cost Efficiency
Securitisation can lead to lower funding costs compared to traditional financing methods, as it often allows for better pricing based on the risk profile of the underlying assets. Recent EU reforms aim to simplify unnecessarily burdensome requirements and reduce costs to encourage more securitisation activity.
Diversification of Funding Sources
By tapping into the capital markets, institutions can diversify their funding sources and reduce reliance on bank financing. This diversification is particularly important in today’s volatile economic environment.
Regulatory Benefits
In some jurisdictions, securitisation can provide regulatory capital relief, allowing institutions to optimize their balance sheets. The European Commission’s recent proposals have estimated a reduction in capital requirements by one-third for senior securitisation tranches, which should encourage new issuances in member states where activity has been limited.
Key Considerations before incorporating a Securitisation Vehicle
The European securitisation market operates under the EU Securitisation Regulation (EUSR), introduced in January 2019 as part of a comprehensive regulatory response to the Global Financial Crisis.
The Securitisation Regulation amendments aim to reduce operational burdens by simplifying transparency requirements, with plans to cut reporting fields by at least 35%. The revisions introduce more proportionate, principle-based due diligence processes, eliminating redundant verification steps when the selling party is EU-based and supervised.
Notably, the requirement for Simple, Transparent and Standardised (STS) securitisations has been modified to consider pools containing 70% SME loans as homogeneous, facilitating cross-border transactions and enhancing SME financing opportunities.2
Choosing the right jurisdiction
Selecting the appropriate jurisdiction for your securitisation vehicle is a critical strategic decision that impacts regulatory compliance, tax efficiency, and operational flexibility. Several European jurisdictions offer competitive frameworks for securitisation vehicles, each with distinct advantages depending on your specific transaction objectives.
The optimal jurisdiction ultimately depends on multiple factors: the location and type of underlying assets, your investor base, anticipated transaction complexity, and specific business objectives. Regulatory changes, such as the EU Securitisation Regulation, have created a more harmonized framework across Europe, though important jurisdictional nuances remain that can significantly impact transaction efficiency.
Structuring the vehicle
Decide on the structure of the securitisation vehicle. Common structures includes:
Securitisation Undertaking: A corporate entity specifically designed for securitisation transactions
Securitisation Fund: Similar to an investment fund, but specifically for securitisation assets
Fiduciary Structures: Where assets are held by a fiduciary for the benefit of investors
These structures are designed to isolate financial risk and facilitate the issuance of securities. You can choose a bankruptcy-remote structure with a Dutch Stichting or a Jersey Trust, which are most commonly used, or incorporate a vehicle using an entity in your group.
Legal & Tax Implications
You’ve made the strategic decision to incorporate a securitisation vehicle—now it’s time to navigate the complex legal and tax landscape that comes with it. Have you considered how different jurisdictional choices might impact your bottom line?
Legal and tax considerations aren’t just compliance checkboxes. They’re powerful levers that can dramatically enhance your securitisation structure’s efficiency. Engaging specialized advisors early in your planning process to avoid costly restructuring later.
By strategically selecting your jurisdiction and structure based on your specific assets and investor profile, you can create a tax-efficient vehicle that maximizes returns while maintaining full compliance.
Servicing and Management
Establish a reliable servicing and management framework for the transaction. Effective management and administration of the vehicle by an experienced partner is critical to ensure the correct execution of the transaction.
As the legislative changes removed restrictions on leverage and the nature of the securities permitted as collateral, the SV can now enter into a facility with a credit institution. This is required to acquire the full amount of the contemplated investments, providing greater certainty to the market.
Conclusion
Incorporating a securitisation vehicle represents a strategic opportunity for financial institutions and asset managers seeking to optimize their capital structures, enhance liquidity, and manage risk effectively. The European securitisation market, with its evolving regulatory framework, offers sophisticated mechanisms to achieve these objectives when properly structured.
Partnering with an experienced service provider gives you access to specialized knowledge from structuring and incorporation to efficient implementation and execution to vehicle liquidation.
This collaboration enables you to navigate jurisdictional complexities with confidence, ensure regulatory compliance across borders, and optimize your structure for maximum efficiency and investor appeal. Such expertise has become not merely beneficial but essential for institutions seeking to leverage the full potential of securitisation.
Securitisation is complex and you shouldn’t have to manage it alone. At Alter Domus, we simplify the process with end-to-end expertise, from transaction closing through administration and up to liquidation. With us as your partner, you can focus on strategy and investors while we take care of execution.
Operational Alpha: a differentiator for venture firms
In a market where venture capital firms are navigating heightened deal investment and fundraising uncertainty, managers are ramping up back-office capability to counterbalance front office risk.
Alter Domus reviews how venture CFOs and COOs are building smarter back offices to support the growth and long-term strategic objectives of their firms.
Tim Toska
Group Sector Head, Private Equity
Venture capital firms are facing the most challenging deal and fundraising backdrop in more than a decade. Investment in operational infrastructure is helping managers to navigate it.
In the first half of 2025 global venture fundraising came in at just US$41.6 billion, according to Venture Capital Journal (VCJ), down from US$60 billion over the same period in 2025 and the lowest first half total in eight years. Venture capital investment volume, meanwhile, fell to a record quarterly low of 7,551 deals in Q1 2025, according to KPMG, with the second quarter not much better as a challenging investment backdrop persisted.
A scarcity of LP allocations and transaction flow has thrown venture capital deployment and fundraising schedules out of kilter and intensified competition between managers for capital and deal flow. In the face of these headwinds, operational excellence is becoming point of difference for managers in a competitive market.
A factor in fundraising
For venture firm CFOs and COOs, the growing importance of the back-office as a differentiator when competing for LP capital is a game changer.
Historically the primary predictor of fundraising success was front office excellence and track record, and the ability of managers to identify and execute on the best deal targets and maximize investor returns. The back office was a necessary but primarily administrative function.
This has been a catalyst for the traditional siloes between the back office and front office breaking down. Operational infrastructure is now a key enabler of front office success, with the CFO and COO setting this interface and participating in the implementation of technology and service provider support to build out of centralized operational processes and data infrastructure that underpin core front office functions.
Indeed, due to the increasing sophistication of the LP base, LPs are paying closer attention to back-office capability when deciding which managers to allocate limited capital resources to. According to Private Funds CFOs 2025 Insights Survey, 36 percent of respondents said LPs were paying closer attention to operational and infrastructure capabilities – up from 22 percent a year earlier.
A robust operating model is seen as a risk mitigator for LPs when selecting managers, as LPs require the managers they back to have the right people, processes and technologies in place to support strong governance and protect firms against downside risk. Alter Domus has noted a steady increase in due diligence requests from investors and prospective investors. These have involved calls, questionnaires and onsite visits to fund administrators.
A sound operational model is also a key enabler for managers to scale as they stay on top of ever-changing fund structures, co-investment, SPVs, continuation vehicles and special account fund structures.
The venture ecosystem hasn’t been isolated from trends reshaping the wider private markets space, where a wider mix of investors, with varying returns objectives and tax and regulatory obligations, comprise a manager’s core LP base. This includes servicing a potentially growing base of non-institutional investors allocating to venture strategies through semi-liquid and interval structures, which require the management of liquidity sleeves and the more regular publication of net asset value (NAV) marks. Venture managers have been pioneers in development of evergreen and permanent fund structures. Blue chip venture managers, including Sequoia and Thrive Capital, are among the venture firms to have launched permanent capital funds with indefinite fund lives. Some of these funds can hold public stocks, a natural fit for early venture investors in what are now some of the world’s largest companies.
In a market where liquidity is at a premium (distributions as proportion of private markets NAV well to 11 percent in 2024, the lowest percentage in a decade, according to Bain & Co analysis, LPs are also placing premium on managers with the back-office capability to manage capital calls and distributions with maximum efficiency.
Cash-constrained LPs will not want to face capital calls too early or have cash locked up unnecessarily because of a premature call. LPs will also note which managers can expedite timelines for distributions. With distributed-to-paid-in (DPI) now almost as important as IRR for LPs when backing managers, the way firms handle cash management processes, capital calls and distributions, has been elevated from relatively low value, administrative work to a key differentiator for LPs.
Venture regulatory and reporting demands are also intensifying. In addition to meeting LP expectations for more frequent and granular reporting on fund and portfolio company performance, venture firms are also having to steer through regulatory change, with the next iteration of the EU’s Alternative Investment Fund Managers Directive – AIFMD II – applying from April 2026, and the US Securities and Exchange Commission (SEC) issuing record levels of financial penalties in the 2024 fiscal year. With data privacy regulation and environmental, social and governance (ESG) compliance also on the venture manager to do list, the regulatory and reporting ask of venture firms has never been more demanding.
The challenge of scaling the back-office
For the venture CFO and COO, who are responsible for laying the foundations and strategic direction of their franchises, an innovative approach to overhauling old expectations of how a firm’s venture back office looks and operates has become necessary to put firms on the right trajectory.
Keeping up with the expanding expectations of the venture capital back-office presents significant cost challenges and complexity for managers, and it is the responsibility of the CFOs and COOs to lead the organizational transformation required to keep their firms in tune with changing market dynamics.
Venture firms have long-operated as nimble, efficient partner-led organizations focused predominantly on deal execution and fundraising. Back-office requirements were relatively light touch and could be handled by small, inhouse teams.
In the current market, CFOs and COOs are under the pressure to determine the best course of action; continue with the in-house model and invest in hiring and growing the team, along with implementing technology to manage increasing operational workload; or partner with service providers.
Exploring the options: insourcing vs outsourcing
Historically venture managers have been slower to adopt an outsourced model than other asset classes. Venture structures have been relatively straightforward to administer, especially for emerging managers where structures may be simple and the volume of investors per fund small enough to manage effectively inhouse. For many of the smaller VCs, cost sensitivity has been another factor for insourcing.
There is also a sensitivity around confidentiality. Several venture deals will be confidential, which has led to some nervousness about sharing too much information with third-party service providers.
The insourcing model, however, does present challenges that venture CFOs and COOs have to consider.
To keep up with increasing complexity, investor expectations and regulatory demands, back-office teams are leaning more and more on technology, software, process automation and AI tools. Advances in technology will also be led by many of the companies that venture managers have invested in and are familiar with. As a result, venture managers will be more familiar and comfortable with automation, AI and new technology, and will find technology more valuable and easier to implement.
The private markets industry has already embarked on this technology trajectory, with an industry survey led by Alter Domus and Deloitte recording that well over half of managers are already utilizing digitization and automation in daily operations, and that almost 63 percent anticipate that AI and GenAI will have a significant impact on the alternative investment industry. The survey found that respondents saw streamlining operational processes, enhancing decision-making capabilities, and increasing portfolio performance areas where digitization and tech-adoption should focus.
Keeping pace with tech adoption, upgrading and transitioning legacy technology platforms, and training and recruiting back-office teams that are fit for purpose, however, requires significant upfront capital expenditure that can prove overwhelming for venture managers – especially if this investment would otherwise have been directed into core front office dealmaking resources and recruitment.
According to VCJ, the average venture fund in H1 2025 closed at US$124.5 million, the lowest average recorded in six years. With smaller funds and fee income than other private markets strategies, such as buyouts or private credit, venture firms will often lack the budgets to add to inhouse teams, invest in new technology platforms and retain back-office staff who are being stretched as reporting and regulatory workflows increase.
Outsourcing presents a solution to these capital expenditure and tech-adoption bottlenecks.
Outsourcing fund administration specialists service thousands of managers and funds, across multiple asset classes and geographies, and are thus able to achieve economies scale that enable them to deliver high-value fund accounting, fund administration and investor services as significantly lower costs than an individual venture manager in isolation.
Fund administrators will also be engaging with regulatory and technology developments, on behalf of clients, on a daily basis and have the scale to deploy dedicated teams with deep expertise in these areas to support venture clients.
Outsourcing providers can also advise venture managers on the software and technology platforms best matched to a manager’s deal strategy and investor base, and leverage relationships with technology vendors to roll-out bespoke solutions at competitive price points that can be benchmarked by LPs.
Fund administrators can also provide venture clients with access to proprietary and automation tools that are fit for purpose, allowing managers to reinvest in other aspects of their business. Alter Domus, for example, has invested significant capital in data analytics and workflow automation, which clients can use to drive efficiencies across the back-office. Clients using these tools have reported efficiency gains of between 10 percent and 20 percent.
The evolution outsourcing
The fund administration industry, however, has recognized some of the challenges presented by “old-fashioned” outsourcing arrangements and has tailored services that allow venture managers to retain the ready access to data and institutional knowledge that an insourced model provides, at the same time as unlocking the cost-efficiencies and scale that an outsourced model can offer.
Fund administrators can now provide co-sourcing operating models where data is held in a cloud environment, rather than behind an administrator firewall, and can be accessed by both manager and fund administrator as required.
For CFOs and COOs this removes the friction points of going back and forth to an administrator when fielding LP information requests, but still gives the manager the back-office scalability and cost advantages of an outsourced model.
In addition, co-sourcing makes it easier to switch administrators if a manager chooses to, as the manager retains control of the platform and software its back-office data is running on.
Lastly, another outsourcing model that growing managers have found compelling is the “lift out”. This involves a number of the manager’s incumbent team leaving and becoming employees of the fund administrator, while continuing to support the same funds they covered in-house. Institutional knowledge isn’t lost, and the manager retains continuity of the team servicing the funds, while putting in place a more scalable and cost-effective operational model for the future.
Building partnerships
As the venture capital ecosystem faces an operational inflection point, where operational infrastructure evolving from a back-office matter to strategic differentiator, working with a tech-enabled fund administration provider can help venture managers to level up their back-office capability without drawing resources and senior partner attention from the core business of raising and deploying capital and delivering returns to LPs.
Relationships between managers and outsourcers, however, are deepening and becoming more sophisticated, to best meet manager requirements.
A fund administrator is no longer just providing arms-length services and basic support, but serving as long-term partner to managers as their operational requirements develop and change.
Managers will now turn to their fund administrators for advice on the optimum operational model for their organization and support on how to execute business transformation, manage data migration and implement new systems. Fund administrators will also advise on the technology and software that best dovetails with a manager’s operational model and keep managers up to date on regulatory and compliance requirements.
A fund administrator like Alter Domus can provide genuine strategic value to venture capital CFOs and COOs as they navigate the shifting industry backdrop, serving not just as provider of basic support functions, but as an important partner and counsel.
Venture capital investment has grown strongly through the first quarter of 2025, despite a volatile macro-economic backdrop. AI investment has been the primary engine of the asset class’s resilience, but other sector themes have also driven deal flow.
Tim Toska Group Sector Head, Private Equity
In the face of volatile stock markets, tariff uncertainty and sustained elevated interest rates venture capital investment has proven remarkably resilient. In the first three months of 2025 global venture investment reached a 10 quarter high of US$126.3 billion and up 53 percent year-on-year from US$82.3 billion in Q1 2024, according to KPMG figures.
Investment in AI and machine learning technology funding rounds has been the single biggest driver of venture capital investment resilience, accounting for close to 60 percent of combined venture deal value in Q1 2025, according to Pitchbook.
But while the importance of AI to the health for the venture deal ecosystem in the current market is undeniable, but behind the AI-driven headlines, other sectors are also generating and interest and deal flow.
Alter Domus reviews five key sectors attracting investment from venture capital managers:
1. AI and machine learning:
Without the contribution of AI funding round activity, overall venture capital funding round investment figures would have come in much weaker.
AI has been a hot ticket for investors, with the long-term growth trajectory and application of AI technologies supporting robust valuations and investor appetite for exposure to fast-growing AI start-ups with proven technologies.
The US AI space has been particularly active, with OpenAI, the developer of ChatGPT, closing the largest private tech in history with a US$40 billion funding round that valued the business at US$300 billion. In other US AI deals large-language model (LLM) competitor Anthropic raised US$4.5 billion across two closings and AI-powered augmented reality company Infinite Reality raised a US$3 billion round to lock in a US$12.5 billion valuation.
AI investment activity also corner-stoned the European venture market, although the focus was more on AI-industrial applications as opposed to the LLM deals that led the US market. Healthcare-led AI companies such as Neko Health and Cera landed funding rounds of US$260 million and US$150 million respectively.
AI also animated Asian venture capital, with the release of Chinese LLM AI company DeepSeek, which can operate with less computing power than other models, opening up AI to a wider pool of users and driving Asian technology giants Alibaba and Tencent to launch their own AI-offerings.
2. Healthtech and biotech:
The healthtech and biotech segment also showed positive investment growth, rising by 30.4 percent in Q1 2025 to reach US$3.5 billion from 185 transactions.
Investment in health and biotech has benefitted from overlaps with the red-hot AI sector, with numerous large funding rounds secured by businesses straddling both segments, such as the abovementioned deals involving preventative healthcare group Neko Health and in-home care platform CERA.
But while AI shaped investment in healthtech and biotech, other sector verticals have also managed to progress funding rounds. Windward Bio, for example, a clinical stage drug developer, landed a US$200 million Series A funding round, while FIRE1, a medical devices developer focused on heart failure care, landed a US$120 million round.
Other funding rounds – for companies spanning a range of therapeutic drug research, digital health technology and scanning and drug delivery areas – have also progressed, illustrates the sustained interest in the healthcare space from venture capital investors.
3. Cleantech
Despite policy shifts in the US on energy transition and environmental, social and governance (ESG), cleantech and climate-focused assets have continued to attract interest from investors.
Even as the policy focus on energy transition shifts, venture capital investors around the world have continued to bank on the long-term requirement for diversified energy sources, energy security and decarbonization in all modern economies.
In the US, X Energy, a developer of small, modular nuclear technology, raised US$700 million in an upsized Series C funding round, while Helion, a fusion reactor business, raised US$425 million in a Series F round.
Outside of the US, Chinese cleantech group SE Environmental secured a US$688 million round, while German real estate energy management company Reneo and Australian vertical farming group, Stacked Farm, closed rounds of US$624 million and US$150 million respectively.
4. Defencetech
Escalating conflict in Eastern Europe and the Middle East, coupled with a shift to satellite-, autonomous- and AI-powered defense system has supported a strong growth in defencetech venture investment, with CB Insights forecasting that at the current run rate defencetech investing will reach US$6 billion by end of 2025 – a 62 percent increase on 2023 levels.
In Europe funding round highlights have included sizeable funding rounds for Defence AI software company Helsing and drone manufacturer, Tekever. The US generated even bigger defensetech deals – including a $600 million raise by autonomous naval defense technology group Saronic Technologies, a $240 million raise for aerospace-focused ShieldAI, and a $250 million raise by anti-drone systems developer Epirus.
5. Fintech
The fintech sector has been focused on the exits and realizations of existing assets, but investment opportunities have continued to emerge, with CB Insights tracking an 18 percent quarter-on-quarter increase in fintech funding to US£10.3 billion for Q1 2025.
A rally in investment in crypto and blockchain assets, including large rounds such as the US$2 billion deal for Maltese crypto exchange Binance, contributed to the increase in fintech investment, with a number of crypto assets also testing out markets for exits.
Outside of the crypto and blockchain space, Mexican buy-now-pay-later (BNPL) platform Plata secured a US$160 million round to achieve unicorn status, while Israeli fintech services provider Raypd landed a US$500 million round to support its acquisition of PayU.
Other areas to watch:
In addition to the core investment themes listed above, venture managers have also kept tracking longer-term investment trends. These are other investment themes to watch:
6. Quantum computing:
Quantum computing – an advanced form of computing based on the principles of quantum mechanics – has the potential to solve calculations and complex problems that current computing systems can’t deliver.
The sector is still relatively nascent, but venture managers are moving actively to build exposure to the sector, with quantum computing groups raising more than US$1.25 billion in Q1 2025 – more than double the year-on-year comparison.
As the sector moves into the commercial domain, and is not solely used in a research and development context, more commercial applications and investment opportunities are opening up.
7. Graphene:
Graphene – a feather-light but incredibly strong substance with huge potential across the construction, manufacturing and industrials sectors – is expected to grow at a compound annual growth rate (CAGR) of 35.1 percent between 2024 and 2030 and become a US$1.61 billion market, according to Grand View Research.
Compared to other venture verticals, funding rounds are still relatively small, but with demand for the substance expected to increase across the energy storage, aerospace and car-making industries, this is an area venture firms are going to be paying ever closer attention to.
8. Synthetic biology:
Synthetic biology – a science applying engineering principles to living systems – has the potential to transform the availability of personalized medicine and food production and is forecast to grow at a compound annual growth rate (CAGR) of 23.2 percent between 2025 and 2035, according to Vantage Market Research.
Venture capital players have invested steadily in synthetic biology research, but commercial applications are still some way off and transitioning the sector from one receiving steady private sector capital flows at seed level, into a sector the presents an attractive risk-reward proposition for venture investors deploying scale-up levels of capital is still some way off.
9. Robotics:
Venture investment in robotics has cooled since 2021, when funding rounds totaled US$14.7 billion versus around US$7.5 billion last year, according to Dealmakerreports.
The sector, however, has continued to attract sizeable, albeit concentrated funding rounds, as companies combine physical robotics capability with AI tools.
Physical Intelligence, for example, a start-up that develops “brains” for robots secured a US$2 billion valuation when closing its recent US$400 million funding round.
In another notable deal Apptronik, a humanoid robotics company based in Texas, closed a Series A funding round at US$350 million. The company is building intelligent robots that can be deployed in the manufacturing, health care and social care sectors, among others.
Global venture capital in 2025: A bifurcating market
Headline venture capital investment figures point to an asset class in rude health, but in reality, the picture is more complex. Alter Domus reviews the drivers behind strong investment levels and why some parts of the venture market and performing better than others.
Tim Toska
Group Sector Head, Private Equity
At first glance, the global venture capital market appears to be booming.
Venture capital investment in Q1 2025 climbed to a 10-quarter high of $126.3 billion, rising from $118.7 billion in the previous three months, according to KPMG; some 35 Unicorn assets (start-ups valued at US$1 billion or more) were formed through the quarter, the second highest quarterly total since 2023, according to Pitchbook, and generative AI platform OpenAI landed a record setting US$40 billion funding round at the end of March.
These headline numbers, however, do not tell the full story. Overall venture investment may appear strong, but the asset class has not escaped the fallout from elevated inflation and interest rates, stock market volatility and global trade uncertainty.
Investment value is up, but venture capital deal volume is down. In Q1 2025 only 7,551 deals crossed the line, down from 8,801 deals in the previous quarter and a record quarterly low, according to KPMG.Meanwhile, a Bain & Co analysis shows a 23 percent year-on-year decline in venture capital fundraising, with Pitchbook recording a year-on-year decline in venture capital exit value, which totaled US$322.8 billion in 2024 versus US$331.2 billion in 2023.
A two-tier market
The gap between robust investment activity on the one hand, and falling fundraising and exit value on the other, reflects the emergence of a two-tier venture market that is bifurcating by sector and size.
Perhaps the starkest contrast to emerge is the widening disparity between the red-hot levels of deal activity involving AI-linked companies and start-ups in other sectors.
Indeed, close to a third of total funding round activity in Q1 2025 was generated by the mega OpenAI funding round, with large-language model AI start-up Anthropic another heavyweight contributor to headline numbers, landing a US$4.5 billion funding round raise. Other companies with specific AI-linked capabilities, including KoBold Metals, a developer of AI-powered mining exploration tools, and AI healthcare company Cera, were among the other high-profile performers.
The dominance of AI and machine learning has been such that it accounted for 57.9 percent of combined venture deal value – an all-time record share of the market, according to Pitchbook.
There have been a few other bright spots in the market, most notably in European defense-focused groups, with the Nato Innovation Fund and Dealroom recording a 24 percent rise in investment in European startups focused on developing defense and defense-related technology. Drone maker Tekever and defense software company Helsing have been among the big winners, as European governments and business ramp up defense spending in response to the ongoing Ukraine war.
Investors and dealmakers appear to be doubling down on select segments of the market, upping investment in these areas while putting investment in other areas on hold until macro-economic uncertainty abates. This is one of the main reasons for falling investment volume at time of rising investment value.
Fundraising falters
Macro-economic volatility has also impacted venture capital in a similar way to the buyout space, with volatility making it increasingly difficult to exit portfolio companies at attractive pricing, which then limits the distributions managers are able to make LPs, who in turn have to put the brakes on supporting new fundraising until managers start returning more cash to investors.
This dynamic has shaped what has been a tough fundraising market – which is expected to remain challenging in the near-term as a much anticipated “exit window” is pushed back yet again.
Venture dealmaker had entered 2025 with quite confidence that the year ahead would herald an improving environment for exits, with IPO markets (a crucial exit channel for venture-backed assets) set to reopen as inflation pressures eased and interest rates assumed a downward trajectory.
Escalating trade tension and tariff uncertainty, coupled ongoing conflict in Ukraine and the Middle East, and associated stock market volatility, however, have pushed back any optimism for a wave of exits back to the second half of 2025 at least, or even into 2026.
Venture-backed companies that have test the IPO waters have struggled to land successful listings at stable prices, while other venture portfolio assets that had been gearing up for big-ticket IPOs have delayed their prospective listings due to market uncertainty.
Exiting via funding rounds involving larger venture firms has also been testing, with Pitchbook noting that in the US – the world’s largest venture ecosystem – more than a quarter of funding rounds in Q1 2025 were flat or down rounds (where a start-up raises money at a lower valuation than in previous funding rounds).
There are signs that trade tariff dislocation may be abating, and stock markets have recovered losses from earlier in the year, laying a firmer foundation for potential exits through the second half of 2025. Markets, however, are still choppy, and it will take time for managers to build the necessary comfort to put companies on an exit pathway.
Opportunities ahead… but uncertainty lingers
Through this period of dislocation, opportunities to invest in high-quality, high-growth venture assets will continue to emerge. AI will more than likely continue to dominate deal activity, although defense and cybersecurity startups will also be high on dealmaker target lists.
Other sectors will also present compelling investment opportunity, although in smaller volumes, with cleantech and fintech the sectors outside of AI and defense that dealmakers are keeping an eye on.
Until there is a sense of wide macro-economic stability, however, the bifurcation theme that has shaped the venture investment during the last 12 months will continue to set the tone for market activity through the rest of 2025.
5 operational challenges faced by venture capital firms
Venture capital (VC) is a form of private equity investment financing that involves investing in early-stage startups with high-growth potential. VC firms aim to generate substantial returns for their investors by fostering the growth of these companies and eventually achieving a successful exit, such as through an IPO or acquisition.
However, despite the promising nature of venture capital, firms often encounter a range of operational challenges that can hinder their ability to manage investments effectively and maximize returns.
In this article, we’ll discuss five key challenges that VC firms commonly face and discuss how leading fund administrators like Alter Domus are helping firms overcome them, streamline operations, and stay focused on delivering investor value.
Challenge 1: Managing capital calls and distributions
Venture capital firms will routinely issue capital calls to draw down committed funds from limited partners (LPs). And when they exit portfolio companies, they will issue distributions.
However, both of these processes come with several challenges that can affect fund efficiency, investor satisfaction, and even regulatory compliance.
For example, capital calls require precise timing.Calling capital too early, i.e.,before the VC firm is ready to deploy it, such as before finalizing a deal, can tie up investors’ cash unnecessarily and lead to frustration. Conversely, calling it too late can lead to missed investment opportunities or cash shortfalls.
Additionally, coordinating capital across multiple LPs can be complicated, especially when managing large or global investor bases. There is also the issue of making sure that each investor’s share of the capital call is calculated correctly. This can also be complicated, especially when the firm is managing a mix of different commitments or investment tiers. Miscalculations can cause legal issues or investor dissatisfaction.
In distribution terms, these often depend on successful exits, which are unpredictable. Timing them to meet investor expectations while preserving portfolio value can be difficult. Also, managing distributions often involves complex calculations to ensure each LP receives their correct share of returns.
Distributions also have tax implications, which can vary by investor. For example, U.S. investors may be taxed differently from foreign investors. Managing these tax complexities while ensuring compliance with local and international tax regulations can be a big challenge for VC firms.
Challenge 2. Navigating complex fund structures
As venture capital firms grow and take on more investors, some often set up different types of funds to meet various needs.
For example, they might create co-investment vehicles for large investors, special purpose entities (SPEs) for single deals, or parallel funds to handle different tax or regulatory requirements.
These structures can unlock strategic advantages for VC firms and attract a wider range of investors. However, they also introduce a host of operational, legal, and compliance challenges for venture capital management.
Having multiple entities of fund structures means more data to track, including fund performance, investor allocations, fees, and distributions. Keeping everything accurate across these entities can be difficult.
Different fund structures may also fall under various regulatory regimes. Keeping up with ongoing filings, disclosures, and audits across jurisdictions can be costly and error-prone.
In the same vein, different fund structures often come with varying tax implications, especially when dealing with cross-border investments. Managing these complexities and ensuring tax efficiency for both the firm and its investors can be a daunting task. Inaccurate tax reporting or inefficient structuring can lead to unexpected liabilities or penalties.
Furthermore, explaining the structure, rights, fees, and returns across different vehicles to LPs can be challenging. Complex structures can obscure performance and increase LP concerns about transparency and alignment of interests.
Challenge 3: Meeting an expanding regulatory environment
As the venture capital and private fund industry, in general, matures, governments and regulatory bodies across the world are ramping up their oversight, creating new compliance burdens that funds must follow.
This expanding regulatory environment poses significant challenges for VC firms.
Complex global regulations:
Many VC firms often execute deals and raise capital from LPs in multiple countries, each with its own set of regulatory frameworks. Adhering to diverse national and international regulations, such as securities laws, tax codes, and anti-money laundering measures, can be cumbersome and time-consuming.
Regulations are continually evolving. A regulatory framework that is compliant today may no longer be so tomorrow. This requires firms to be proactive in monitoring changes and adjusting their strategies accordingly.
Rising compliance and operational costs:
Meeting regulatory demands can be expensive. Firms must invest in compliance teams, legal counsel, and technology systems. These rising costs can strain smaller firms and divert capital away from growth-oriented activities.
Constraints on strategic flexibility:
Regulatory considerations, including ESG-related requirements, may limit the types of investments firms can pursue or slow down decision-making as additional due diligence becomes necessary.
Data privacy and cybersecurity pressures:
Regulations like GDPR impose strict obligations on how personal and financial data is handled. VC firms must ensure strong data protection protocols are in place or risk fines and reputational damage.
Legal liabilities:
With stricter regulatory oversight, VC firms face an increased risk of legal action for non-compliance, which could include monetary fines and penalties.
For example, the SEC reported it had filed a total of 583 enforcement actions against firms in 2024 and secured a record-breaking $8.2 billion in financial penalties, the highest total in its history. Legal action against a firm can lead to reputational damage, which in turn can affect a firm’s ability to attract future investors or raise additional funds.
Challenge 4: Delivering accurate and timely LP reporting
Modern LPs, armed with greater knowledge and a more discerning approach to their investments, are demanding a richer and more frequent flow of information from venture capital management.
However, delivering on these expectations is not without its challenges for VC firms. Here are some hurdles companies currently face.
Complexity of data collection and aggregation:
VC firms often invest in multiple startups, each with its financial systems, performance metrics, and stages of development. Aggregating data from these diverse sources, including equity positions, valuations, fund expenses, and portfolio performance, can be time-consuming and prone to errors.
Valuation challenges:
One of the most significant challenges in VC reporting is valuing early-stage investments accurately. Unlike public companies, which have easily accessible market prices, early-stage startups often lack clear market comparables, making valuations more subjective.
These valuations are typically determined through methods like discounted cash flow (DCF) or using comparable company analysis, both of which can be influenced by assumptions that may not be universally agreed upon.
This subjectivity introduces potential discrepancies between what different LPs consider the “true” value of the portfolio. Furthermore, the valuation of startups can fluctuate dramatically based on the latest funding rounds, exits, or market conditions, making it difficult to provide consistent and reliable valuation data in a timely manner.
Custom reporting requirements:
LPs often have unique reporting requirements based on their investment strategies, risk profiles, and other preferences. Meeting these customized reporting needs while maintaining accuracy and consistency can be challenging, particularly for smaller VC firms with limited resources.
Internal resource constraints:
Many VC firms, especially smaller ones, lack the resources or dedicated staff to manage the heavy workload required for accurate LP reporting. This can lead to overburdened teams, delays, and errors in reporting, which can negatively impact investor confidence.
Manual processes and lack of automation:
Many VC firms still rely on manual processes for collecting, organizing, and analyzing investment data. This increases the risk of errors and delays and makes it challenging to produce accurate and timely reports.
Challenge 5: Scaling operational infrastructure and talent
As venture capital firms grow, success brings a new set of operational demands.
Early-stage VC firms can often function effectively with lean teams, informal processes, and minimal infrastructure. But as they raise larger funds, expand their portfolios, and attract more established LPs, this becomes unsustainable. Firms must scale their operation infrastructure and talent to support this expansion and growth.
But again, many firms experience challenges in this area.
For example, as the firm grows, it needs to hire specialized professionals across various functions, including deal sourcing, legal, operations, and portfolio management. The demand for skilled individuals in these areas is high, and with many firms competing for the same talent, recruitment becomes costly and time-consuming. Finding candidates who not only have the necessary skills but also align with the firm’s culture is a big challenge.
Once the right talent is acquired, retaining it can also be an issue. Failing to build a clear career progression path, offer competitive compensation, or provide sufficient work-life balance can lead to high turnover, which disrupts operations and increases recruitment costs.
Operationally, scaling infrastructure often means higher costs. As the firm’s portfolio and the number of deals increase, so do the demands for more sophisticated systems and tools. Firms must invest in technology and support to handle portfolio management, investor relations, and reporting. These tools can require significant upfront costs for software, licensing, and implementation, and ongoing maintenance expenses.
For many VC firms, outsourcing some of these operational tasks to specialized service providers can be a good practical solution, as we’ll see in the next section.
How outsourced venture capital services address these challenges
To overcome some of the challenges outlined above and streamline their operations, many VC firms are turning to outsourced VC service providers like Alter Domus.
These firms offer the expertise, technology, and dedicated resources needed to manage critical back-office functions that would otherwise consume significant time and effort if handled internally.
For instance, these providers offer advanced fund administration platforms and experienced teams capable of managing every stage of capital calls and distributions. They can handle everything from calculating individual LP obligations to processing payments and providing detailed transaction reporting.
To address the increasing demands of regulatory compliance, these providers often have dedicated compliance teams that stay current with evolving rules. They can assist with developing and implementing compliance programs and managing regulatory filings, thus helping firms stay compliant.
Outsourced service providers can also help VC firms improve the quality, consistency, and transparency of their reporting. These providers typically bring a combination of experienced professionals and purpose-built technology platforms that streamline the reporting process and ensure greater accuracy.
For example, they offer technology and resources to centralize financial and operational data across funds, integrating information from multiple systems into a single, unified platform. This approach reduces the need for manual data entry, minimizing errors and ensuring that all financial information is accurate and up-to-date.
Many service providers offer secure, user-friendly online portals where VC firms and stakeholders can easily access real-time reports, transaction histories, and performance data. This centralized access enhances transparency, allowing firms to share information quickly and efficiently with investors, auditors, and other key parties.
Finally, outsourcing offers a flexible and cost-effective solution for scaling operational infrastructure and talent. Firms gain access to a scalable pool of specialized professionals and technology platforms without the fixed costs and management overhead of building an in-house team.
Wrapping: Venture capital operational challenges
Venture capital firms face a range of operational challenges as they grow and manage increasingly complex portfolios. These challenges as seen include managing capital calls and distributions, meeting expanding regulatory compliance requirements, delivering accurate and timely LP reporting, finally and scaling operational infrastructure and talent.
However, these operational complexities don’t have to hinder growth and success. By strategically partnering with specialized service providers, venture capital firms can access the infrastructure, technology, and expertise needed to tackle these challenges effectively.
Additionally, outsourcing frees up VC firms to focus on what really drives value, which is identifying, investing in, and nurturing high-potential, innovative companies.
How fund administration supports scaling-up venture capital operations
Every venture capital firm aspires to grow with time, whether that means raising larger funds, managing a broader portfolio, or expanding into new markets. However, growth often comes with increased operational complexity.
As the firm expands, managing critical tasks like capital calls and distributions, investor reporting, compliance, and governance in-house can start straining internal resources and divert attention from core fund priorities like sourcing deals and providing strategic support to portfolio companies.
In light of this, many VC firms are increasingly turning to professional fund administration services. These services provide the expertise, systems and infrastructure that VC firms need to scale effectively, without sacrificing operational efficiency or affecting the ability to meet their obligations to investors and regulatory authorities.
In this guide, we’ll dive deeper into the role of fund administrators in helping VC firms scale, including the key functions these entities provide.
Challenges of scaling up venture capital operations
Before we get into how fund administration can enable more efficient scaling, let’s first look at three major operational challenges that many venture capital firms face as they expand their operations.
Increased fund complexity
Scaling a venture capital operation usually includes either launching more funds, managing larger funds, or structuring funds in increasingly complex ways. All these changes add operational strain to the firm.
Increased number of funds: Managing multiple funds, each with its own investment focus, lifecycle, and mandate, creates a higher administrative burden. More funds require more resources to ensure each operates smoothly and in line with its objectives.
Larger funds: Bigger funds demand more disciplined capital deployment, enhanced reporting, and a stronger internal team to manage investor relations.
Complex fund structures: Specialized funds, such as region-specific funds, co-investment vehicles, and special purpose entities (SPEs), introduce additional layers of governance, reporting, and compliance obligations.
Regulatory burdens increase
Growth venture capital firms also tend to increase their exposure to regulatory scrutiny. For example, crossing certain AUM thresholds can trigger mandatory filings with relevant regulators like the SEC. Additionally, more investors mean more Know Your Customer (KYC) and Anti-Money Laundering (AML) compliance work.
International expansion adds additional complexity to regulatory requirements. Firms must follow varying regulations, such as tax codes, disclosure rules, and securities laws, in each jurisdiction where they operate. Staying on top of all regulatory obligations can be quite challenging.
Growing LP demands for transparency
Limited Partners (LPs) are increasingly expecting greater transparency and more comprehensive reporting from General Partners (GPs) in the private equity industry. They wantmore frequent, detailed, and transparent reporting, not just during fundraising rounds, but throughout the fund lifecycle. This includes timely capital account statements, NAV updates, performance metrics, and ESG disclosures.
Meeting these heightened expectations for an increased number of investors and funds can be challenging without the proper mechanisms and support in place.
The good news for VC firms is that these challenges are manageable. One of the most effective solutions is leveraging professional fund administration services.
What is venture capital fund administration?
Venture capital fund administration involves outsourcing back-office tasks to a specialized third-party firm. Essentially, the third-party, known as a fund administrator, takes over the day-to-day operational or administrative tasks, such as fund accounting, investor reporting, and regulatory compliance, that VC firms would otherwise need to manage in-house.
How fund administration helps scale venture capital firms
Fund administration plays a crucial role in supporting firms during periods of expansion by managing the increasing demands of back-office functions. For example, they can provide support in several key areas, including the following.
Streamlining capital call and distribution processes
Fund administration automates and organizes the capital call and distribution workflow, ensuring that these transactions are executed seamlessly and on time. This reduces the manual workload on VC firms, mitigates the risk of errors and improves the overall experience for investors.
Enhancing LP reporting and transparency
Fund administration provides the necessary infrastructure to ensure that all limited partners (LPs) receive timely, accurate, and consistent reports on their investments. Such transparency fosters trust and confidence among investors and helps maintain strong, ongoing relationships as the firm scales its operations.
Supporting regulatory compliance and governance
Fund administrators ensure that VC firms meet all regulatory obligations as they scale by managing the necessary filings and documentation. They handle KYC and AML checks and maintain proper records on these. In addition, fund administrators closely monitor changes in the regulatory environment and advise firms on any changes they might need to make to ensure compliance.
Why outsourcing fund administration makes strategic sense
According to a 2024 Ocorian survey, 99% of private equity, venture capital, and real estate fund managers globally plan to increase outsourcing over the next three years, with nearly half (46%) targeting a 25–50% increase in outsourced functions.
Besides helping firms overcome some of the operational complexities that come with scaling, outsourcing fund administrations offers several other significant advantages.
Cost savings
Building an in-house fund administration team requires significant resources, including hiring specialized staff, investing in technology, and training employees to keep up with changing regulations. As a firm grows, the costs associated with maintaining this infrastructure can quickly add up.
Outsourcing to a third-party fund administrator like Alter Domus, allows VC firms to leverage professional services and technology without the overhead of managing these functions internally.
Access to specialized expertise and evolving best practices
Outsourcing gives VC firms access to professionals who are highly experienced in private fund structures and up to date with the latest regulations, best practices, and financial technologies. This ensures higher accuracy and professionalism across key fund activities, including accounting and investor reporting.
Freeing internal teams to focus on core investing activities
Perhaps one of the most significant benefits of outsourcing fund administration is that it frees internal teams toprioritize sourcing, evaluating, and managing investments.
By offloading the time-consuming and often complex administrative tasks deal teams can dedicate their expertise and energy to identifying promising investment opportunities and actively supporting their portfolio companies. This ensures that the core value-creation activities of the VC firm remain the central focus.
Alter Domus: A partner in venture capital fund administration
If you’re looking for a fund administration partner that offers deep industry expertise, great flexibility, and tailored solutions to support your growth, Alter Domus could be a good fit.
Here’s what you can expect when you partner with Alter Domus:
Comprehensive fund accounting:
Expert management of fund accounting, including investment tracking, valuations, waterfall and carried interest calculations, and much more.
Investor reporting:
Detailed and transparent reporting to keep your investors informed about the performance and health of their investments and the fund in general..
Capital call and distribution processing:
Streamlined management of capital calls and distributions to ensure accuracy and timely execution.
Regulatory compliance support:
Comprehensive guidance on meeting regulatory requirements and maintaining compliance across different jurisdictions.
Tech-driven solutions:
Integration of advanced fund administration solutions designed to automate workflows, enhance operational efficiency, and provide real-time transparency.
Full fund lifecycle management:
End-to-end support, from fund formation through to exit, with tailored services to ensure smooth operation at all stages.
Audit support:
Comprehensive audit assistance, including the preparation of relevant documentation and coordination with auditors to ensure a smooth audit process.
Wrapping up: How venture capital fund administration supports growth
Fund administration plays a key role in the growth of venture capital firms by providing the structure and expertise needed to manage increasing operational demands and complexity. It takes care of administrative tasks like fund accounting, investor reporting, and compliance management, which frees internal teams to focus on what matters most: identifying high-potential investments and driving growth.
With deep industry knowledge and a commitment to excellence, Alter Domus is the ideal venture capital fund administration partner to help streamline operations and support your firm’s growth. Explore Alter Domus venture capital solutions and fund administration solutions to learn more.