

Analysis
As middle-market private equity firms grow, the operating models that supported early success can quickly hit a ceiling.
In the fourth of a six-part series on the middle-market manager, Curtis Beyer and Tim Ruxton of the Alter Domus Client and Industry Solutions team explore why investing in private equity fund operations, data and technology ahead of the growth curve can help firms meet rising investor expectations, attract capital and scale with confidence.
Curtis Beyer
Managing Director,
Client & Industry Solutions
Tim Ruxton
Managing Director,
Client & Industry Solutions
There comes a point in every high-growth business’s development where the operational rails that supported its first wave of rapid expansion begin to creak.
In Japan, management consultants and corporate leaders refer to the “organizational wall”: the point at which previous management models become obsolete and must be overhauled as headcount and revenue clear certain thresholds. McKinsey analysis similarly shows that midsize company performance can flatten when businesses reach a certain scale without refreshing how they work.
For decades, middle-market private equity firms have helped portfolio companies move through these growth inflection points by professionalizing management teams, deepening finance capabilities and upgrading technology infrastructure.
But while private equity managers have concentrated on supporting portfolio company business transformation, they have focused less on upgrading their own operations.
This is changing. Private capital assets under management (AUM) have increased 18-fold over the last two decades and currently stand at around US$18 trillion.
GPs are responsible for stewarding materially larger sums of capital, invested by increasingly global investors, and have to institutionalize their franchises to absorb current demand and lay the foundations to support future growth.
Most middle-market private equity firms will encounter similar organizational inflection points as they evolve from boutique firms with small investor bases into larger organizations deploying institutional capital.
At the start of this growth cycle, when emerging middle-market managers are finding their feet and completing their first deals, firms are characterized by small teams and limited fee income. At this stage, GPs will typically be managing a single private equity fund that will rarely exceed US$250 million. Fund administration is relatively simple at this phase. Operations teams can be kept lean, while core fund accounting and investor reporting can be outsourced to a third-party provider. Investors in these GPs will usually participate through emerging manager programs and accept that operational infrastructure is still being built.
If successful, emerging managers face their first organizational inflection point as they transition into small-cap and lower-middle-market private equity firms. Operational complexity begins to build during this phase of development, according to consultancy network Umbrex.
GPs will have raised two or more flagship funds by this stage, and if performance is sustained, fund sizes will expand at an accelerated pace. Sidecar funds and co-investment funds will also come into the frame, as managers in the segment begin to source deals that can’t be accommodated by current funds. This places higher demands on operations teams, as they have to report and account for more investment vehicles.
The operational demands continue to intensify as firms graduate to the next phase and move into the core and upper-middle-market brackets, where investor expectations for reporting and disclosure increase and managers expand into new geographies or launch new investment strategies.
Middle market GPs in these segments are managing international office networks, building in-house value creation teams, institutionalizing the investor relations function, adopting Institutional Limited Partners Association (ILPA) reporting guidelines and producing environmental, social, and governance (ESG) reports.
As firms approach each of these inflection points, deeper operational, technology and data capabilities become increasingly mission-critical to meeting more demanding regulatory and compliance obligations.
Upfront investment in operational infrastructure allows GPs to mitigate risk as their franchises progress through the operational inflection points highlighted above.
For a high-growth middle-market firm in the earlier stages of development, the benefits of making a large upfront investment in operations rather than front-office deal capability are not immediately obvious. One attribute shared by many middle-market firms that scale successfully, however, is that they build institutional infrastructure before it becomes essential.
Proactively scaling up operational capability, rather than trying to backfill capacity retrospectively, creates long-term competitive advantages and unlocks operational alpha. Investing in systems and processes ahead of growth mitigates the risk of operational drag, where fundraising and AUM growth are restricted by internal bottlenecks. These bottlenecks can constrain a manager’s ability to onboard more investors, absorb more capital and produce higher volumes of fund and investor reporting without compromising quality.
Building operational scale ahead of growth does not simply mean expanding headcount to execute a higher volume of the same tasks. It involves using technology to streamline workflows, automate manual processes and connect portfolio, fund and investor data, enabling faster reporting and deeper performance insight.
Data management is one of the primary levers middle-market private equity managers can use to move from an entrepreneurial GP with limited operational infrastructure to an established firm with an institutional-grade operating backbone.
Internal data can be moved out of manual spreadsheets and into a cloud-based data warehouse that connects with specialist private markets software for fund accounting and customer relationship management (CRM). Software tools with effective APIs are a key enabler of automation. When systems are connected, data from a deal recorded in the CRM can flow automatically into portfolio monitoring and accounting tools without manual re-entry.
Effective data management also supports cleaner, faster LP and regulatory reporting. Manual responses to LP requests and reports emailed as PDFs, for example, can be replaced with secure, on-demand LP portals and self-service dashboards.
Middle-market GPs do not have to manage this operational overhaul in isolation. An outsourcing or co-sourcing partner may already have the technology, data infrastructure and specialist expertise to support growth, freeing the GP’s CFO to focus on higher-value strategic priorities such as liquidity management, tax structuring and portfolio analysis.
As middle-market private equity firms prepare for fundraising, a new strategy or entry into another market, three questions can test operational readiness:
• Can fund accounting, investor reporting, compliance and data processes support more funds, investors and jurisdictions without weakening controls?
• Is data connected across CRM, portfolio monitoring, fund accounting and investor reporting, with clear ownership and governance?
• Which capabilities should remain in-house, and where could outsourcing or co-sourcing add scale, resilience and specialist expertise?
The answers should guide the operating model and choice of partner. Alter Domus supports middle-market managers from core fund accounting and reporting to multi-jurisdictional operations.
Through our work with private markets managers globally, we’re seeing several consistent themes emerge.
Operational investment is happening earlier. Rather than waiting until assets under management reach a certain scale, managers are strengthening operating models ahead of fundraising to demonstrate institutional readiness from the outset.
Investor expectations are converging. Limited partners increasingly expect middle market managers to deliver the same standards of reporting, governance and transparency as much larger firms. The difference between manager tiers is becoming less about expectations and more about how efficiently those expectations are met.
Operating decisions are becoming strategic decisions. Investments in technology, data management and fund administration are no longer viewed simply as efficiency initiatives. Increasingly, they are enabling growth, supporting fundraising and helping managers scale with confidence.
The CFO’s role is expanding. Finance leaders are playing a broader role in shaping operating models, evaluating technology investments and strengthening investor reporting. Operational excellence is becoming a strategic capability, not just a finance function.
Managers are looking for flexibility, not complexity. The firms making the greatest progress are not necessarily building larger operational teams. They are finding ways to access institutional-quality capabilities while preserving the agility that has long differentiated the middle market.
United States
Managing Director, North America


United States
Managing Director, North America
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields
Analysis
For middle market private equity managers, operational resilience is becoming a competitive advantage. The right operating model can reduce key person risk, strengthen LP reporting and help firms adapt to regulatory, cybersecurity and fundraising pressures.
In the third of a six-part series, Curtis Beyer and Tim Ruxton of the Alter Domus Client and Industry Solutions team assess why operational resilience is becoming a competitive advantage for middle market private equity managers.
Curtis Beyer
Managing Director,
Client & Industry Solutions
Tim Ruxton
Managing Director,
Client & Industry Solutions
The private equity middle market is the engine room of the industry.
It accounts for almost three quarters of the pool of investable companies, and for the last 20 years top quartile middle market funds have outperformed their large cap counterparts by 4.5%, according to analysis from Pantheon.
For decades this outperformance has been driven by entrepreneurial middle market private equity firms led by concentrated teams of experienced dealmakers, who leveraged personal networks and individual deal skills to originate proprietary deal flow and generate strong returns on exit.
The formula for middle market private equity success, however, is changing as the industry expands and the deal market shifts. Global private equity assets under management (AUM) have grown more than ten-fold over the last 25 years to exceed US$10 trillion, according to KKR. The industry is bigger, more competitive and increasingly sophisticated, and delivering returns is becoming more difficult as entry multiples increase, leverage multiples moderate and financing costs rise.
Today, private equity’s growth, coupled with the high levels of uncertainty managers and investors face at this point in the cycle, poses significant challenges for the resilience of the traditional middle market private equity operating model.
Allocations to private equity are substantially larger, making LPs more sensitive to downside risk and less comfortable with depending entirely on a handful of veteran managers to steward capital through a particularly volatile market.
When a firm’s dealmaking experience, track record, and accumulated knowledge are tightly concentrated in the hands of a few senior partners, a firm becomes vulnerable.
This fragility becomes more apparent in market headwinds, when the volume of crucial decisions multiplies and firms grapple with dips in portfolio company earnings, delayed exit timelines and prolonged fundraising. Concentrated leadership and a lack of established processes make senior partners a bottleneck for urgent decision-making in a market where responsiveness is essential. In the worst-case scenario, where the pressure becomes too great, a concentrated leadership structure can fracture irreparably.
Key person risk, often referred to as key man risk, has always been on the radar for LPs. With more capital now at stake and a tougher operating environment to contend with, this sensitivity has heightened even further.
Operational resilience means having the processes, systems and organizational depth to keep a private equity firm functioning as people, markets and requirements change. LPs are therefore seeking managers that can demonstrate this depth, rather than depending entirely on specific individuals. Personnel changes are not the only disruption a resilient operating model must be prepared to absorb.
Middle market private equity managers can build this fund operations infrastructure without adding significant headcount or taking on high upfront capital investment.
Automation, technology and agentic AI are allowing smaller GPs to reimagine the volume and quality of work their operational teams can produce (see Part 2 in the series). By partnering with a global third-party fund services provider, they can access private equity fund administration, accounting and reporting technology without building those capabilities from scratch.
The way middle market private equity firms operate is changing, but the expertise and technology are available to help GPs make the leap from successful entrepreneurial firms, where performance is inextricably linked to the founders, to operationally resilient institutions that can thrive through whatever comes next.
As technology becomes more embedded in private equity operations, LPs are also factoring managers’ readiness to withstand cyber disruption and regulatory change into allocation decisions.
Cybersecurity is front of mind for all financial institutions. More than four-fifths (82%) of banks, insurers and asset managers surveyed by the Bank of England cited cyberattack as a top-five risk to the financial system, up 10 percentage points from the previous poll.
Organizations are also increasingly economically exposed to cloud infrastructure outages. The cost of system downtime, according to research from Splunk Technology, a Cisco company, has climbed 50% during the last two years and led to a 3.4% average decline in the equity values of the Global 2000 companies.
These risks are not confined to large organizations and pose real challenges for middle market private equity managers, who investors increasingly expect to meet the same standards of contingency planning and risk management as much larger firms. LPs expect GPs, irrespective of size, to have business continuity plans, fallback systems and emergency protocols in place to recover from disruption and continue delivering core functions.
The resilience of GP operations has been further stretched by continuous regulatory change. The UK’s Financial Conduct Authority (FCA) is consulting on reforms to the UK Alternative Investment Fund Manager (AIFM) regime that could lead to rule changes across valuations, liquidity risk management, annual reporting, investor disclosures and marketing. The European Commission is proposing amendments to the Sustainable Finance Disclosure Regulation (SFDR), tightening eligibility criteria for ESG-linked financial products; and the US Securities and Exchange Commission (SEC) is reportedly increasing scrutiny of potential conflicts of interest in continuation vehicle (CV) deals, as well as opening examinations of private fund valuations.
Increasing regulatory workloads have been matched by intensifying LP expectations around fund reporting, transparency and disclosure. LPs are pushing GPs to include special rights to view internal fund information in fund documentation, particularly around sensitive issues such as asset valuations and conflicts of interest.
There are ongoing challenges for GPs to address, and the margin for error is narrowing.
A multi-firm review of valuation processes for private market assets published by the FCA in 2025 found that most firms only partly identified and documented valuation-related conflicts linked to investor marketing, secured borrowing, asset transfers, redemptions, subscriptions, uplifts and volatility. It also found that many firms did not have defined processes for ad hoc valuations during market events.
This was echoed in the most recent Institutional Limited Partners Association (ILPA) LP Sentiment Survey, which recorded a decline in LP perception of GP behavior with respect to governance terms, conflicts of interest and valuations.
Middle market private equity managers that tackle these LP concerns head-on are gaining an edge in a crowded market, but doing so requires a resilient operating model that can improve and deepen LP reporting and disclosure.
Resilient operating infrastructure is also fundamental for middle market firms seeking to diversify their investor bases in a tight fundraising cycle and unlock capital through alternatives to the 10-year closed-end fund. According to McKinsey, separately managed accounts, co-investment and evergreen fund structures have boosted global private equity AUM by trillions.
New private equity fund structures present middle market managers with a significant opportunity to grow their franchises, but they also add complexity to fund operations. More structures must be administered, often with additional reporting requirements such as producing monthly net asset value (NAV) figures for evergreen vehicles.
Firms that lack rigorous operational infrastructure will struggle under the weight of these demands, while better-prepared competitors will be positioned to grow.
Alter Domus gives middle market managers access to a private equity fund services platform with a level of operating resilience that is difficult for a GP to replicate in isolation.
Our global team of 7,000 professionals combines private markets expertise with leading technology to stay ahead of regulatory change and shifting reporting expectations. We have the depth and infrastructure to scale middle market fund operations, helping managers adapt quickly as requirements and workloads increase.
A platform of this size also has the resources and economies of scale to make sustained investment in proprietary technology, automation and AI commercially viable.
GPs can use this outsourced operating infrastructure and scale it with their own growth, without incurring the upfront capital and ongoing maintenance costs of building it in-house.
As a proven global operator that maintains ISO and SOC accreditations for business continuity management, internal controls and information security, Alter Domus has the tools to help middle market firms maintain continuity when faced with uncertainty, and adapt to change with confidence.
Through our work with private markets managers globally, we’re seeing several consistent themes emerge.
Operational investment is happening earlier. Rather than waiting until assets under management reach a certain scale, managers are strengthening operating models ahead of fundraising to demonstrate institutional readiness from the outset.
Investor expectations are converging. Limited partners increasingly expect middle market managers to deliver the same standards of reporting, governance and transparency as much larger firms. The difference between manager tiers is becoming less about expectations and more about how efficiently those expectations are met.
Operating decisions are becoming strategic decisions. Investments in technology, data management and fund administration are no longer viewed simply as efficiency initiatives. Increasingly, they are enabling growth, supporting fundraising and helping managers scale with confidence.
The CFO’s role is expanding. Finance leaders are playing a broader role in shaping operating models, evaluating technology investments and strengthening investor reporting. Operational excellence is becoming a strategic capability, not just a finance function.
Managers are looking for flexibility, not complexity. The firms making the greatest progress are not necessarily building larger operational teams. They are finding ways to access institutional-quality capabilities while preserving the agility that has long differentiated the middle market.
United States
Managing Director, North America
United States
Managing Director, North America
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields
Analysis
The role of the company secretary is central to ensuring compliance, governance, and smooth corporate operations, yet its definition and legal standing vary widely across Europe. This article explores the jurisdictional differences between common law and civil law countries, and why clarity on governance responsibilities is vital for global organizations.
Behind every well-governed company is a framework of processes, records, filings, and decision-making support that helps preserve good standing and regulatory compliance. The company secretary plays a central role in that framework, helping organizations meet statutory and regulatory obligations while supporting the effective administration of corporate entities.
Although the role is sometimes perceived as administrative, it often carries significant strategic responsibilities. As expectations around corporate governance continue to rise, this function is increasingly recognised as a key guardian of lawful, transparent, and well-documented corporate decision-making.
In practice, the company secretary often acts as the operational link between the board, the company, shareholders, regulators, and advisers, ensuring that meetings, filings, records, and communications are managed effectively.
The role of a company secretary can encompass all areas of a company’s activities, depending on the size and nature of the organisation. These activities typically fall into three principal categories:
The company secretary ensures proper board procedures are established and followed, prepares and circulates board materials, and provides practical guidance to directors. They serve as a crucial advisor on governance matters, keeping the board informed of relevant legislative and regulatory changes.
A fundamental aspect of this position involves maintaining statutory registers, organising board and shareholder meetings, preparing minutes, and ensuring the company complies with all applicable legal and regulatory requirements. This includes managing annual returns, coordinating statutory filings, and overseeing changes to company structures.
The company secretary often serves as the primary point of contact between the company and its shareholders, ensuring effective information flow and communication. They facilitate dialogue between the board, shareholders, and other stakeholders, promoting transparency and accountability.
The role and legal requirements of a company secretary vary significantly across European jurisdictions, reflecting broader differences between common law and civil law systems.
In common law jurisdictions like the United Kingdom and Ireland, the company secretary role is integrated into company law and treated as a formal function. This officer, usually appointed by the Board, has extensive duties and responsibilities including statutory filings, compliance, board governance, shareholder communication, and transactional support.
In the United Kingdom, public companies must appoint a company secretary, while private companies may choose to do so.¹ The position can be filled by either an individual or a corporate body. UK company secretaries are responsible for statutory filings with Companies House, board support, and shareholder communication.
Similarly, in Ireland, all companies must have a company secretary.² The role focuses on statutory compliance, transaction management, and filing obligations with the Companies Registration Office (CRO).
In many civil law jurisdictions, including Luxembourg, France, and Germany, there is no equivalent statutory office of company secretary. The underlying responsibilities are typically handled by a law firm, external service provider, in-house legal team, paralegal professional, or another governance specialist.
France and Germany similarly have no specific statutory position of company secretary in their corporate law. Governance and compliance duties are often divided among legal counsel, managing directors, and external advisors.
Luxembourg presents an interesting case study in the evolution of the company secretary role. While there is no formal legal requirement for this function, its responsibilities — including board administration, legal record-keeping, and liaison with the Registre de Commerce et des Sociétés (RCS), where applicable — are increasingly recognised in practice. This reflects a broader shift as investors, regulators, and other stakeholders place greater emphasis on Environmental, Social, and Governance (ESG) standards, with initiatives such as the “Corporate Governance Officer” certification created by the Luxembourg Institute of Governance (ILA) for professionals in governance functions.³
Regulatory scrutiny of genuine governance substance has intensified across Europe, particularly in Luxembourg and other key fund jurisdictions. Regulators are looking beyond documentation to assess whether real decision-making is taking place at board level — examining meeting frequency, board composition, and the quality of governance records. The company secretary plays a critical role in evidencing that substance, ensuring that governance is not just technically compliant but demonstrably real.
The need for robust governance also extends beyond regulatory compliance. Shareholders, investors, auditors, potential buyers, and other stakeholders increasingly scrutinise the quality of a company’s governance framework as part of their own due diligence. In a fundraising, audit, or M&A context, gaps in entities’ statutory records — such as missed filings, incomplete minutes, or unclear decision-making trails — can raise red flags, delay transactions, or affect valuations. Good governance is therefore not only a regulatory obligation; it is a mark of organisational credibility and a driver of commercial confidence.
For companies operating across multiple jurisdictions, clear ownership of corporate governance responsibilities and a practical understanding of local requirements are business necessities. Failure to meet local corporate compliance obligations can lead to:
The fragmented regulatory landscape across Europe creates significant oversight challenges for multinational organisations. As regulatory scrutiny intensifies and corporate structures grow more complex, businesses increasingly recognise the challenge of maintaining consistent in-house expertise across multiple jurisdictions and may look to third-party providers for specialist support.
When assessing whether to use external corporate secretarial support, organisations should consider several practical benefits:
The adoption of AI-assisted tools across entity management, statutory tracking, minute-taking, and board portals has accelerated rapidly. For multinational organisations managing complex corporate structures across multiple jurisdictions, technology is no longer a nice-to-have — it is central to delivering accurate, efficient, and scalable governance. Leading company secretarial service providers are increasingly leveraging these tools to reduce risk and improve turnaround times. However, technology should support — not replace — human judgement, local expertise, proper review, and board accountability.
As corporate governance continues to evolve across Europe, the company secretary position is gaining further prominence, even in jurisdictions where it currently lacks formal recognition.
While not every jurisdiction requires a formally appointed company secretary, the underlying responsibilities remain essential: ensuring compliance, supporting effective board processes, maintaining reliable records, and demonstrating good governance substance.
For multinational organisations, clarity over who owns these responsibilities is critical. Whether supported internally, externally, or through a hybrid model, effective company secretarial support helps preserve good standing, reduce regulatory and transaction risk, and build confidence with boards, shareholders, investors, auditors, and other stakeholders.
1 Companies Act 2006, c. 46, § 271-273. (2006). UK Public General Acts. https://www.legislation.gov.uk/ukpga/2006/46/part/12/chapter/1
2 Companies Act 2014, § 129. (2014). Irish Statute Book. http://www.irishstatutebook.ie/eli/2014/act/38/enacted/en/html
3 Luxembourg Institute of Gvernance. (2023). Corporate Governance Officer certification. https://www.ila.lu/education/certified-programs/certified-programs-description/corporate-governance-officer
Analysis
Higher private markets reporting demands are increasing operational workloads for middle market fund managers. Adding capacity to keep pace with intensifying requirements, however, doesn’t inevitably mean hiring ever larger teams.
In the second of a six-part series, Curtis Beyer and Tim Ruxton of the Alter Domus Client and Industry Solutions team assess how the best-performing operations teams at middle market firms are harnessing automation and data to increase capacity, and unlock value, without ramping up costs.
Curtis Beyer
Managing Director,
Client & Industry Solutions
Tim Ruxton
Managing Director,
Client & Industry Solutions
Across the private markets industry, firms are having to process larger data volumes from more sources to back up investment decisions and keep pace with reporting and regulatory demands.
An S&P Global GP and LP survey found that more than three-quarters of respondents (77%) reported using at least 50% more data sources than five years ago. More than a third (37%) said the number of data sources they used had more than doubled.
Managing increasing data workloads is a challenge for all firms, but has a proportionally bigger impact on middle market fund managers that run lean back-office teams and lack resources to absorb escalating workloads.
Smaller middle market managers don’t benefit from the same levels of fee income, or economies of scale, that large private markets platforms enjoy. Investing large sums of upfront capital expenditure in upgrading technology infrastructure can, therefore, prove financially prohibitive for smaller franchises, who instead continue to rely on manual processes and growing headcount to keep up with higher operational demands.
This can leave smaller GPs carrying a much higher per-dollar staffing burden than their larger peers, according to McKinsey. Smaller firms tend to employ between 22 and 30 people per US$1 billion of AUM, but firms with US$5 billion to US$10 billion employ only nine.
For middle market managers, the capacity dividend is the opportunity to deploy technology to bring down the costs of growing operational demands while freeing existing resources to focus on investors and fundraising.
The middle market model of hiring more staff to handle more data is simply becoming unsustainable, both from a cost and a reliability perspective.
Firm budgets can only accommodate increasing operations headcount to a point, but even if the higher headcount costs are feasible, increasing the number of people involved in data and reporting processes throws up other challenges, heightening the risk of data bottlenecks and manual errors.
Middle market firms with the best-performing operations and finance teams have acknowledged these constraints and are shifting to a new operational model that builds capacity without ramping up costs and headcount.
Technology sits at the center of the new model, and best-in-class middle market finance teams are deploying technology to automate repetitive and low-value work.
Operations teams that have made the transition to a technology-powered operating model, for example, are using technology to scan, review and extract data from portfolio company reporting packs and upload it to portfolio management systems, while process automation is streamlining workflows that would otherwise require multiple manual checks and approvals.
Agentic AI is taking this capability to another level again. Private markets software developer Allvue notes that AI agents have the capability to autonomously track, check and correct data in real time while maintaining complete audit trails.
This enhanced operational capability can improve the speed and quality of a firm’s output without having to bring in more staff to keep up with increasing operational complexity.
Better systems also make existing staff more effective, and free operational teams from spending time on monotonous tasks, like reconciliations, allowing them to add value to the core functions of fundraising and investor relationships.
Middle market GPs that can aggregate fund data in a single place and deliver investor reporting with greater speed and accuracy will gain a competitive edge over peers with similar investment track records.
In a recent LP survey, investors cited lack of access to analytics and disparate LP dashboards with multiple logins as the biggest bugbears with GP technology infrastructure. Firms that have invested in these areas, and can free up operational teams to focus on simplifying information access and transparency, will have more satisfied LPs.
The operational resources released as a result can also enable middle market firms to launch and run a wider variety of investment vehicles, separately managed accounts and co-investments – an increasingly important capability for unlocking capital from LPs that want to make larger allocations to middle market strategies, but often through alternative structures to 10-year closed-end funds.
Technology gives firms the headroom to improve the investor experience and ultimately pursue growth without having to expand operational teams at the same pace.
Building the data and technology capability to implement process automation and agentic AI, however, can be a daunting task for managers. In its 2026 GP Survey, MSCI found that 48% of respondents identified advanced data, technology and AI as the greatest capability gap.
Closing that gap is not simply a matter of buying more technology. Capacity is created when data, systems and workflows operate as a single model. Routine processes can then be standardized and automated, information can move consistently across funds and vehicles, and teams can absorb additional complexity without having to recreate the operating infrastructure each time.
For middle market managers, this changes the build-versus-partner calculation. The question is not whether every capability should sit in-house, but which activities are central to differentiation and which can be supported by a specialist operating partner.
A partner can provide the underlying data framework, technology and execution depth for functions such as fund administration and investor reporting. This allows the manager’s own teams to retain oversight while spending more time on investors, fundraising and product development.
Alter Domus supports this model by combining operational expertise with integrated data and technology infrastructure. The objective is not simply to process more work. It is to create an operating platform that can accommodate new reporting demands, additional vehicles and growth without costs increasing at the same rate.
As operational demands rise, managers that make this shift will have more than an efficient back office. They will have created capacity that can be reinvested in the areas that drive growth.
Through our work with private markets managers globally, we’re seeing several consistent themes emerge.
Operational investment is happening earlier. Rather than waiting until assets under management reach a certain scale, managers are strengthening operating models ahead of fundraising to demonstrate institutional readiness from the outset.
Investor expectations are converging. Limited partners increasingly expect middle market managers to deliver the same standards of reporting, governance and transparency as much larger firms. The difference between manager tiers is becoming less about expectations and more about how efficiently those expectations are met.
Operating decisions are becoming strategic decisions. Investments in technology, data management and fund administration are no longer viewed simply as efficiency initiatives. Increasingly, they are enabling growth, supporting fundraising and helping managers scale with confidence.
The CFO’s role is expanding. Finance leaders are playing a broader role in shaping operating models, evaluating technology investments and strengthening investor reporting. Operational excellence is becoming a strategic capability, not just a finance function.
Managers are looking for flexibility, not complexity. The firms making the greatest progress are not necessarily building larger operational teams. They are finding ways to access institutional-quality capabilities while preserving the agility that has long differentiated the middle market.
United States
Managing Director, North America
United States
Managing Director, North America
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields
Analysis
Fundraising across private markets is becoming increasingly selective. At the same time, investor expectations of managers continue to evolve.
For established middle market managers, this is changing the basis of competition. Investment performance remains essential, but investors are increasingly looking beyond returns to assess the institutional capability of the managers they back.
In the first of a six-part series, Curtis Beyer and Tim Ruxton of the Alter Domus Client and Industry Solutions team explore why operational excellence is emerging as one of the defining competitive advantages in today’s private markets landscape.
Curtis Beyer
Managing Director,
Client & Industry Solutions
Tim Ruxton
Managing Director,
Client & Industry Solutions
For years, middle market private markets managers have competed through disciplined investment decision-making, strong portfolio execution and consistent value creation. Those capabilities remain fundamental to success, but they are no longer enough in isolation.
The rules of competition are changing. As fundraising becomes more selective and LPs apply greater scrutiny to manager selection, investors are looking beyond historical performance toward organizational capability. Returns remain essential, but they are increasingly accompanied by a new question: does this manager have the operating maturity to steward investor capital throughout the full life of a fund?
For middle market managers that have earned their place in investor portfolios through consistent performance, the emergence of operational capability as another manager selection criterion represents a significant shift. Reporting, governance, operating discipline and investor experience are no longer viewed simply as support functions. They have become indicators of institutional quality and, increasingly, a source of competitive advantage.
Together, these capabilities form the operating model that enables managers to scale efficiently, meet investor expectations and support sustainable long-term growth.
This reflects more than higher operational expectations. In a market characterized by slower distributions, constrained liquidity and more selective capital allocation, institutional investors have greater opportunity to compare managers across every aspect of their business. An effective operating model has become an important indicator of how successfully a manager can manage complexity, respond to change and deliver a consistent experience throughout the life of a fund.
For CFOs and finance leaders, that represents an important shift. Decisions once viewed primarily through the lens of operational efficiency increasingly influence fundraising, investor confidence and a firm’s ability to scale.
Meeting these expectations requires investment in technology, data management, compliance, risk management and finance functions that are often easier for larger organizations to absorb because of their scale. Without the fee income or operational footprint of the industry’s largest platforms, many middle market managers face an important strategic question: how do they build institutional-quality operations while preserving the agility that has always differentiated them?
Importantly, many middle market managers have also demonstrated strong investment performance relative to larger peers. Yet today’s fundraising environment suggests that strong returns alone are no longer enough to differentiate a firm. Investors are increasingly looking beyond performance, assessing whether managers have the operational capabilities to deliver consistent execution, governance and long-term growth.
In this first article of a six-part series, Alter Domus explores why operational excellence is moving beyond the back office and becoming one of the defining competitive advantages in today’s private markets landscape.
The impact of rising expectations is already visible in today’s fundraising market.
Global fundraising exceeded US$260 billion during the first six months of 2026, putting the market on track to surpass the previous year’s annual total by 17%. However, only 310 funds reached a final close during the same period, meaning the number of successful fundraises is projected to fall significantly year on year.
Capital is concentrating in the hands of fewer managers. As competition for allocations intensifies, every aspect of a manager’s business is coming under greater scrutiny. That changes the basis of competition. In stronger fundraising markets, investment performance alone could often secure investor attention. Today’s environment is different. Operational capability is emerging as another factor that separates managers competing for the same pool of capital.
Performance dispersion remains an important contributor to fundraising concentration. However, investors are also placing greater emphasis on the confidence that comes from robust governance, transparent reporting and disciplined execution throughout the investment lifecycle.
Increasingly, investors view a manager’s operating model as an indicator of institutional capability. The ability to deliver consistent reporting, robust governance and timely insight provides confidence that a manager can deploy capital effectively, navigate complexity and steward investor capital throughout the life of a fund.
For established middle market managers, the implication is clear. Competing successfully for capital increasingly depends on more than a differentiated investment strategy. Investors want confidence not only in how capital will be invested, but also in how it will be governed, reported and managed over the life of the fund.
For CFOs, this means the finance function is becoming a strategic enabler of growth rather than simply a steward of financial control. Increasingly, the strength of the operating model influences not only operational performance, but investor confidence and fundraising success.
Operational excellence has therefore moved beyond the back office. It is becoming a defining characteristic of institutional-quality managers and an increasingly important source of competitive advantage in today’s fundraising environment.
The question facing middle market managers is no longer whether they need institutional-quality operations. Increasingly, they do. The challenge is how to build them without sacrificing the agility that has long been their competitive advantage.
For CFOs and finance leaders, that increasingly means making operating decisions that support not only operational efficiency, but future fundraising, investor confidence and long-term growth.
The good news is that building institutional-quality operations does not necessarily require building every capability in-house. By partnering with a trusted fund administration provider, managers can access institutional-quality operating infrastructure without making disproportionate investments in technology, reporting, compliance and operational teams.
Working with a specialist partner gives middle market managers access to operating capabilities that are already running at scale. Rather than recreating institutional infrastructure internally, managers can leverage proven operating models that have evolved alongside some of the world’s most sophisticated private markets firms. These include experienced private markets professionals, technology platforms, investor reporting, regulatory and compliance expertise, and global delivery models designed to support increasingly sophisticated investor requirements.
Rather than continually expanding internal teams or investing in multiple technology platforms, managers can leverage an established operating model that scales alongside their business. This enables firms to retain lean operating teams while benefiting from institutional-quality governance, reporting and operational processes.
The result is greater flexibility. Internal resources remain focused on the areas that create the greatest value—including investment execution, portfolio oversight, liquidity management and investor relationships—while core operational activities are supported by scalable infrastructure that evolves alongside the business.
For middle market managers, there is no single blueprint for building institutional-quality operations. Each firm brings its own investment strategy, operating model, investor expectations and growth ambitions — and the operational infrastructure supporting them should reflect that reality.
Avoid a one-size-fits-all approach
Applying a standardised operating model rarely accounts for the nuances of a firm’s strategy or structure. The more effective approach is to build operational capabilities that are specifically aligned to how a firm operates and where it is heading.
Plan for operational evolution
As firms grow, investor expectations tend to become more sophisticated and operational complexity increases. Fund accounting, investor reporting, governance, compliance and data management requirements all evolve with scale — and the infrastructure supporting them should be designed to keep pace, rather than adapted reactively.
Preserve agility while building institutional credibility
One of the defining characteristics of successful middle market managers is their ability to move quickly and remain close to their investments. Operational build-out should strengthen investor confidence without introducing the rigidity that can slow decision-making or limit flexibility.
Align operational capability to long-term growth objectives
Operational foundations are most effective when they are built with a firm’s long-term trajectory in mind. Scalable operating models allow investment teams to remain focused on performance and value creation, rather than being pulled into operational challenges as the business grows.
Middle market managers have long differentiated themselves through investment expertise, entrepreneurial thinking and the ability to respond quickly to changing market conditions. Those strengths remain fundamental to long-term success.
Increasingly, however, investors are evaluating more than investment capability alone. They are looking for confidence that managers can deliver consistent reporting, robust governance and an operating model capable of supporting long-term growth.
Much of this evolution is being led by finance teams. As operational expectations increase, CFOs are taking a broader role in shaping technology investment, operating models and investor reporting.
Operational excellence is therefore no longer simply about running a more efficient back office. It has become part of how managers demonstrate institutional capability to existing and prospective investors. It is about creating the institutional capability that inspires investor confidence, supports sustainable growth and strengthens a manager’s ability to compete in an increasingly selective fundraising environment.
For middle market managers, the firms that combine investment excellence with institutional-quality operations will be best positioned to win capital, deepen investor relationships and sustain growth over the long term.
Through our work with private markets managers globally, we’re seeing several consistent themes emerge.
Operational investment is happening earlier. Rather than waiting until assets under management reach a certain scale, managers are strengthening operating models ahead of fundraising to demonstrate institutional readiness from the outset.
Investor expectations are converging. Limited partners increasingly expect middle market managers to deliver the same standards of reporting, governance and transparency as much larger firms. The difference between manager tiers is becoming less about expectations and more about how efficiently those expectations are met.
Operating decisions are becoming strategic decisions. Investments in technology, data management and fund administration are no longer viewed simply as efficiency initiatives. Increasingly, they are enabling growth, supporting fundraising and helping managers scale with confidence.
The CFO’s role is expanding. Finance leaders are playing a broader role in shaping operating models, evaluating technology investments and strengthening investor reporting. Operational excellence is becoming a strategic capability, not just a finance function.
Managers are looking for flexibility, not complexity. The firms making the greatest progress are not necessarily building larger operational teams. They are finding ways to access institutional-quality capabilities while preserving the agility that has long differentiated the middle market.
United States
Managing Director, North America
United States
Managing Director, North America
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields
Analysis
As credit markets become increasingly complex, we examine how loan-level stress testing provides the insight needed to anticipate losses, validate assumptions, and strengthen portfolio resilience.
In today’s volatile financial landscape, the ability to anticipate and navigate potential economic downturns is not just a strategic advantage it’s a necessity for financial institutions. As credit portfolios become increasingly complex and economic uncertainty persists, stakeholders must prioritize the implementation of sophisticated stress testing frameworks that deliver accurate, actionable insights into portfolio vulnerabilities and capital adequacy.
By adopting a loan-level stress testing approach that integrates directly with CECL-based frameworks, institutions can gain invaluable insights into their credit portfolios, enabling them to identify vulnerabilities, optimize capital allocations, and enhance strategic decision-making.
Traditional portfolio-level stress testing approaches often rely on broad approximations and static assumptions that fail to capture the nuanced dynamics of credit risk migration. These methods treat portfolios as homogeneous blocks, applying uniform stress factors across diverse loan types, borrower profiles, and risk characteristics. Such approaches may provide directional guidance but lack the granularity necessary for precise capital planning and robust risk management.
A loan-level stress testing framework addresses these limitations by applying stress directly to individual borrower financial indicators, such as debt service coverage ratios (DSCR), net operating income (NOI), revenue trends, FICO scores, and small business risk indicator (SBRI) scores. This granular approach recognizes that borrower behavior and credit portfolio performance demonstrate heightened sensitivity to hypothetical economic scenarios that are unique to each institution.
By stressing these loan-level variables and predicting subsequent credit rating movements, institutions can forecast the resulting impacts on CECL allowances, provisions, net charge-offs (NCOs), and capital with remarkable accuracy.
One of the most compelling advantages of a sophisticated loan-level stress testing framework is its seamless integration with existing CECL infrastructure. While CECL estimates reflect expected losses under baseline or reasonably supportable forecasts, stress testing extends this analysis to more adverse economic scenarios. The integration of both frameworks enables a comprehensive assessment of portfolio risk and capital adequacy.
By feeding predicted loan-level risk rating changes directly into an institution’s CECL exposure at default (EAD) model, the framework produces accurate impacts on allowances, earnings and capital. This approach leverages the actual CECL-based cash flow model with its detailed payment and risk characteristics—including contractual amortization terms, funded and unfunded amounts, default probabilities, loss given default assumptions, and prepayment rate curves—to deliver period-by-period forecasts over the specified horizon.
This methodology represents a substantial improvement over approximations, particularly because the progression of credit losses is path-dependent and rarely follows a linear pattern. The framework captures the dynamic interplay between portfolio runoff, new loan originations, risk rating migrations, and loss realization timing—factors that static models cannot adequately address.
The technical foundation of modern loan-level stress testing frameworks combines quantitative rigor with qualitative judgment through advanced machine learning techniques. Predictive models, including Decision Tree, Histogram Gradient Boosting, and Random Forest Classifiers, are trained on historical credit data to identify patterns in rating migrations under various stress conditions.
A key methodological innovation involves developing separate upgrade and downgrade models for each portfolio segment to address class imbalance issues where downgrades historically outnumber upgrades. These models utilize sophisticated performance metrics like F1 scores rather than simple accuracy, employ class weights to balance predictions, and incorporate ordinal classifiers with monotonic features to ensure logical stress responses.
This approach ensures that as borrower financial metrics deteriorate under stress, predicted rating downgrades increase proportionally—a critical validation step that enhances model credibility and regulatory acceptance.
The framework typically segments portfolios based on loan characteristics and data availability, for instance, large commercial real estate loans may be modeled using detailed financial statement variables, while consumer loans rely more heavily on credit scores and payment behavior. This segmentation enables each model to leverage the most predictive variables for its respective borrower population.
Perhaps the most significant value proposition of a loan-level stress testing framework is its ability to produce comprehensive multi-period projections rather than single-period snapshots. By incorporating roll-forward functionality with realistic loan growth assumptions, the framework dynamically updates the portfolio composition at each period throughout the forecast horizon, typically on a quarterly basis over one or more years.
This capability enables institutions to assess not only the initial shock from adverse conditions but also the cumulative impacts as stress persists and portfolio composition evolves. The framework produces forecasts of expected losses, provisions, NCOs, and capital ratios across the planning horizon, supporting both risk management and internal strategic planning initiatives. Institutions can evaluate their degree of compliance with relevant capital ratio thresholds—such as minimum Common Equity Tier 1, Tier 1, and Total risk-based ratios—while weighing the likelihood of various scenarios.
These frameworks are most effective when supported by fully integrated technology platforms that unify CECL compliance, multi-scenario stress testing, and portfolio analytics within a single auditable infrastructure. Alter Domus’ ALLL+ Platform delivers CECL compliance and credit loss estimation with integrated scenario management, real-time attribution analysis, and governance capabilities ensuring full audit traceability, while the Analytics Platform (formerly Risk Modeler) extends this into strategic portfolio management through macroeconomic default regression, loan-level risk classification, and real-time portfolio monitoring.
When these capabilities share a common data infrastructure, institutions gain a materially clearer view of embedded portfolio risk. Advanced machine learning further enhances this visibility by surfacing complex patterns that traditional approaches overlook, translating analytical rigor into more informed decisions around capital allocation, underwriting, and strategic planning.
The risks associated with credit portfolios are multifaceted and can vary significantly across institutions, influenced by factors such as borrower behavior, market conditions, and organizational objectives. Credit portfolio compositions differ across financial institutions based on strategic objectives, risk appetite, expertise, geographic presence, and organizational mission. Consequently, both borrower behavior and portfolio performance may demonstrate unique sensitivities to economic scenarios, making tailored stress testing essential, a necessity further reinforced by OCC guidance.
Regular and rigorous stress testing through a sophisticated loan-level framework serves as a cornerstone of sound risk management. It helps institutions identify vulnerabilities within portfolios—particularly those arising from excessive concentrations in specific borrowers, industries, geographic regions, or product types. This proactive approach not only safeguards against potential losses but also positions institutions to make informed strategic decisions regarding underwriting standards, credit policy refinements, and capital allocation optimization.
In an uncertain economic environment, institutions that embrace advanced loan-level stress testing frameworks will be better positioned to navigate challenges and thrive.
To learn more about AlterDomus’ integrated risk management solutions, contact [email protected].
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields
Analysis
In the first part of its Real State of Real Estate series, Alter Domus explored why specialist real estate investment strategies are supplanting traditional, generalist models.
In the second instalment in the series, Alter Domus examines the practical implications of what the trend towards specialization means for real estate managers, and how firms are evolving their operational models to keep pace with the growing complexity inherent in managing multi-strategy real estate platforms.
Michael Gregori
Head of Real Estate, North America
Melanie Collett
Head of Real Estate, EMEA
The real estate investment model is in a period of significant transformation. To remain competitive and effective, managers must evolve their operational models in step with the demands of an increasingly complex landscape.
Twenty years ago, real estate portfolio construction was a relatively simple exercise. Office assets accounted for the bulk of portfolio composition, topped up with a mix of other familiar real estate categories, such as retail and residential.
Pandemic lockdowns and the recent cycle of rising interest rates have changed that. Office share of real estate portfolios is around a third of what it used to be in 2008, according to Blackrock. McKinsey, meanwhile, notes that deliberate asset selection has replaced broad-based real estate exposure as the primary driver of returns performance.
The traditional real estate asset verticals of office and retail still have a role to play, but data centers, life sciences, storage, senior living, and myriad other real estate sub-sectors are now essential for driving real estate returns. Investor preference isn’t only specializing by type of asset, but also investment strategy. Core and core-plus investment strategies target IRRs in the mid-single digits to low teens. Value-add and opportunistic strategies carry greater risk, but target higher returns in the upper teens.
Investors are also broadening allocations beyond real estate equity plays into real estate credit and real estate asset-based finance (ABF) to fine-tune portfolios in line with specific risk-adjusted returns targets.
Today’s institutional platforms routinely span multiple specialist sectors and jurisdictions, and the portfolios they manage demand fund structures that are equally sophisticated and fit for purpose.
McKinsey notes that creative capital structuring at the asset and fund level can serve as drivers of real estate outperformance. NAV loans, continuation vehicles, structured secondaries and hybrid capital structures offer the flexibility to extend hold periods, bridge liquidity gaps and reposition portfolios.
Private real estate is also tracking the wider trend across private markets of managers running a broader spread of fund structures.
GPs are offering a wider range of fund structures, separately managed accounts, co-investment funds and evergreen investment vehicles. These structures address the specific requirements of institutional investors, and facilitate access for non-institutional investors to private real estate strategies.
The transition toward specialist investment strategies in real estate, and the structural flexibility required to support it, is adding meaningful layers of operational complexity for firms across the industry.
Fund accounting teams are under mounting pressure to manage a growing number of fund structures, investment strategies and global jurisdictions. As portfolio breadth increases, maintaining consistency across multiple strategies and structures becomes considerably more challenging, and the consequences of reporting errors and delays grow more significant.
Investment strategy complexity is adding operational burden for real estate back-office teams. This compounds when combined with increasing demands for LP reporting and transparency.
In all private market strategies, asset-level transparency and portfolio aggregation are becoming table stakes. LPs want to see granular, real-time data on asset performance that facilitates forward-looking decision-making, rather than retrospective, reactive portfolio management.
For a time, real estate managers were able to absorb increasing workloads by stretching legacy systems and processes, but that approach has reached its limits. As fund structures continue to proliferate, manual reconciliations become unmanageable, and the risks of reporting errors and data fragmentation escalate, making a fundamental step change in operational models not just desirable, but necessary.
Upgrading real estate models is essential. Data has to be standardized, and automation and AI leveraged to manage operational complexity.
LPs, across all private markets strategies, are adapting manager selection decisions accordingly. Reporting and accounting teams are no longer simply cost centers, but key enablers of competent portfolio stewardship and headline returns.
Managers with the capability to track valuations at both the asset and portfolio level, and to benchmark performance consistently across real estate strategies, hold a meaningful competitive advantage. Operational capability is far more than a compliance requirement; it is a reliable predictor of long-term performance success.
Building up real estate investment platforms to scale is one of the ways managers are addressing the complexity challenge. When firms reach a certain size, investment in technology, data and AI can be spread more evenly across multiple strategies and funds, unlocking economies of scale.
For mid-market players, however, ramping up platform size is not the only pathway to achieving the back-office economies of scale available to larger counterparts.
Specialization is valued in today’s market, and managers operating in lucrative industry niches will not want to trade off distinctive front office capability for back-office scale.
Partnering with a specialist third-party fund administrator allows independent real estate firms to access the geographic reach and technological capabilities of a large-scale platform, without the burden of significant upfront capital expenditure, or the need to relinquish independence by merging into a larger manager.
Alter Domus serves more than 400 real estate clients worldwide, administering US$380 billion in real estate assets across 1,250 real estate funds and separate accounts.
With a deep real estate client base and a global presence in 24 jurisdictions, Alter Domus brings both the geographic reach and asset-specific technical expertise that modern real estate managers demand. Our Integrated Global Real Estate Solution (IGRES) brings this together, layering advanced technology across a fully integrated, end-to-end administration service, from the asset level through to investors.
Integrated operating environments like IGRES are designed to consolidate property-level and fund-level accounting, consolidation, investor reporting, debt administration and data integration into one reporting architecture.
This unified operating environment marks a significant departure from the back-office models that have historically definedreal estate administration. Where property managers and fund accountants once operated across disconnected systems, SPVs were tracked in isolation, and investor reporting was produced manually, a more integrated and efficient approach is now possible.
Fragmented back-office services can handle smaller, simpler portfolios, but begin to fracture as portfolios become larger and more specialized.
An integrated stack addresses this risk and empowers managers to handle higher workloads and complexity without data splitting and operational burden escalating.
The real estate asset class is specializing rapidly, and operational infrastructure is emerging as a defining competitive advantage.
Specialization introduces layers of structural complexity that legacy operating models are simply not equipped to support and technology stacks assembled informally over time cannot deliver at scale.
The firms best positioned to succeed will be those that pair deep sector expertise with integrated operating models capable of delivering centralized reporting and institutional-grade transparency across even the most complex portfolios.
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields
Analysis
We explore how financial institutions can move beyond backward-looking risk management by adopting forward-looking CECL frameworks, multi scenario stress testing, and portfolio analytics to proactively identify emerging credit risks.
The U.S. auto loan market has undergone structural shifts that are reshaping credit risk. Post-COVID vehicle price increases have driven loan balances significantly higher, while extended terms—increasingly exceeding 72 months—mask affordability challenges. Simultaneously, widespread negative equity from trade-ins has pushed loan-to-value ratios above 100% at origination, with monthly payments frequently surpassing $1,000.
These compounding dynamics intensify credit risk in recent loan vintages, requiring financial institutions to move beyond backward-looking risk management toward forward-looking analytical frameworks consistent with CECL assumptions that identify vulnerabilities before losses materialize. Alter Domus’ integrated platform combines CECL compliance, multi-scenario stress testing, and real-time portfolio analytics to enable institutions to proactively identify and monitor loans exhibiting multiple risk characteristics.
The auto loan market has evolved during the post-COVID period in ways that compound several key credit risk factors, leaving lender’s portfolios vulnerable to potential economic downturns.
Credit risk indicators from 2021-2024 loan vintages are beginning to show stress patterns compared to pre-pandemic performance. Analysis of auto loan portfolios from AD’s consortium database reveals additional evidence of these stress indicators as demonstrated in the accompanying exhibits, yielding several key observations.
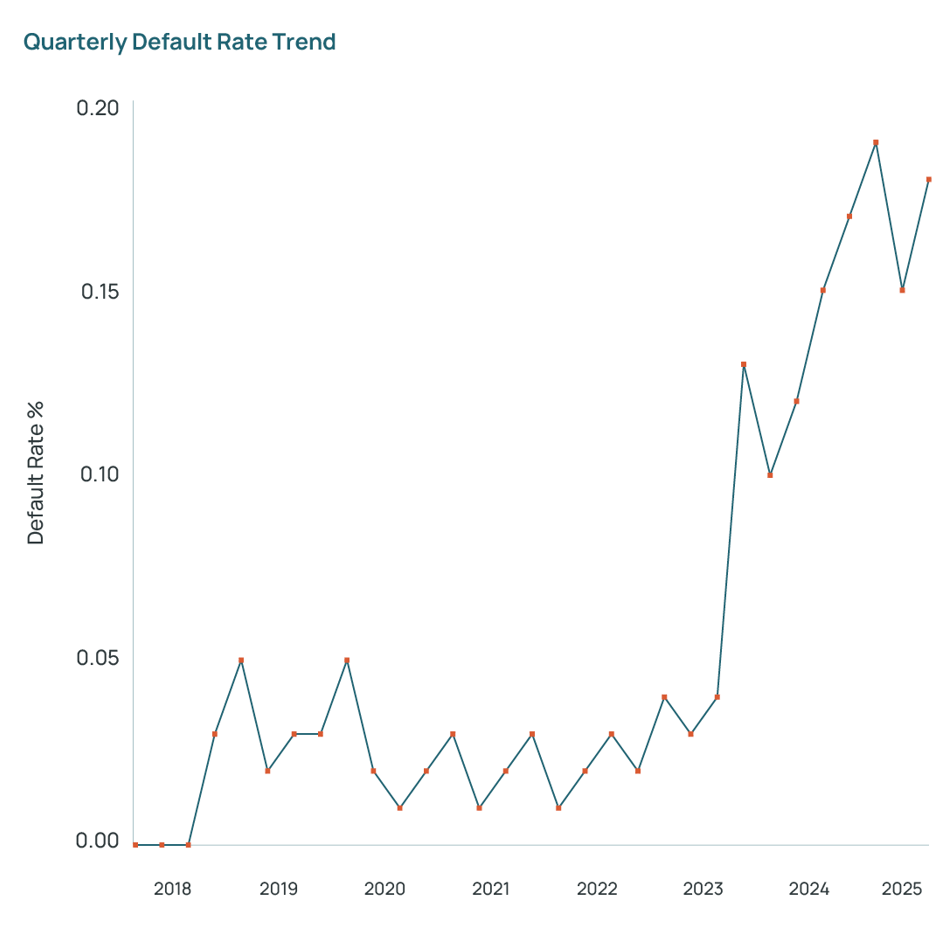
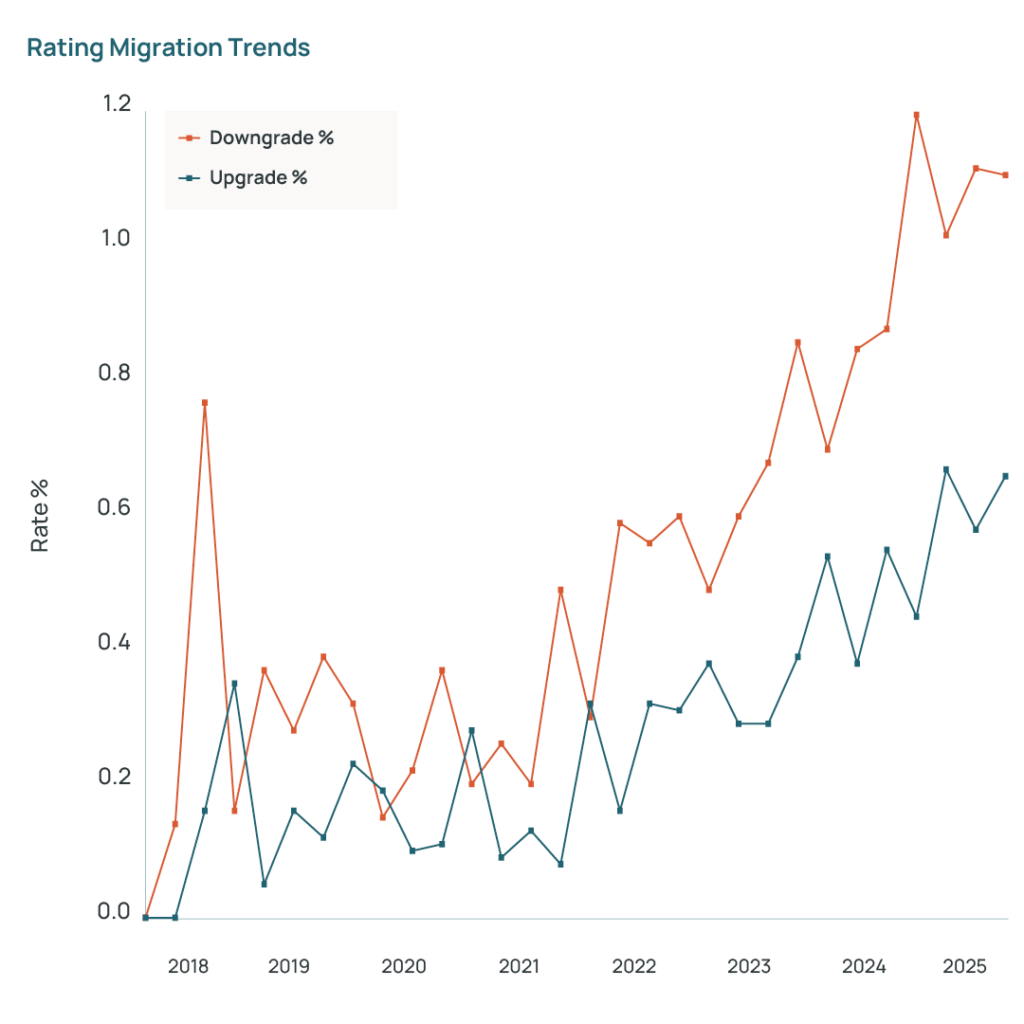
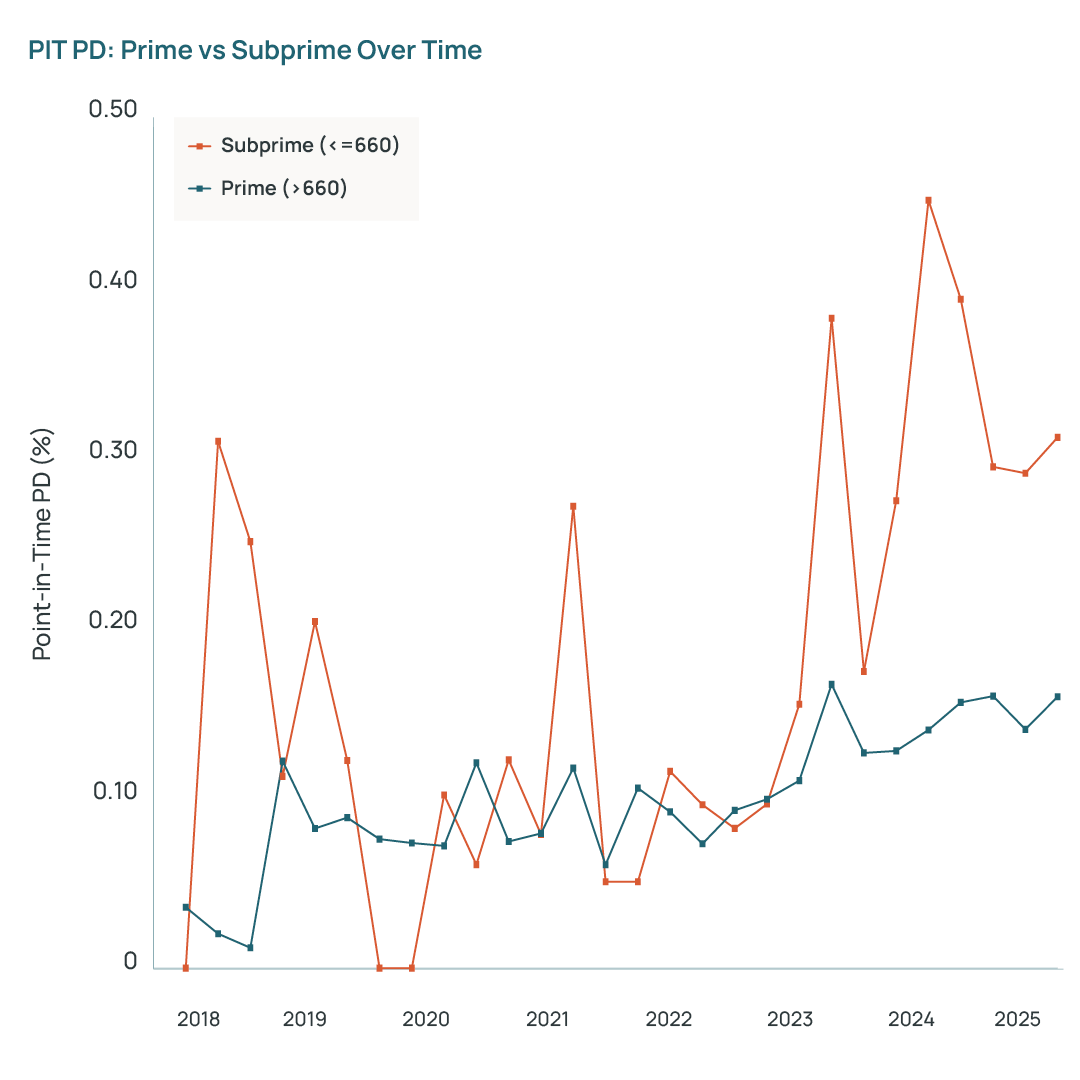
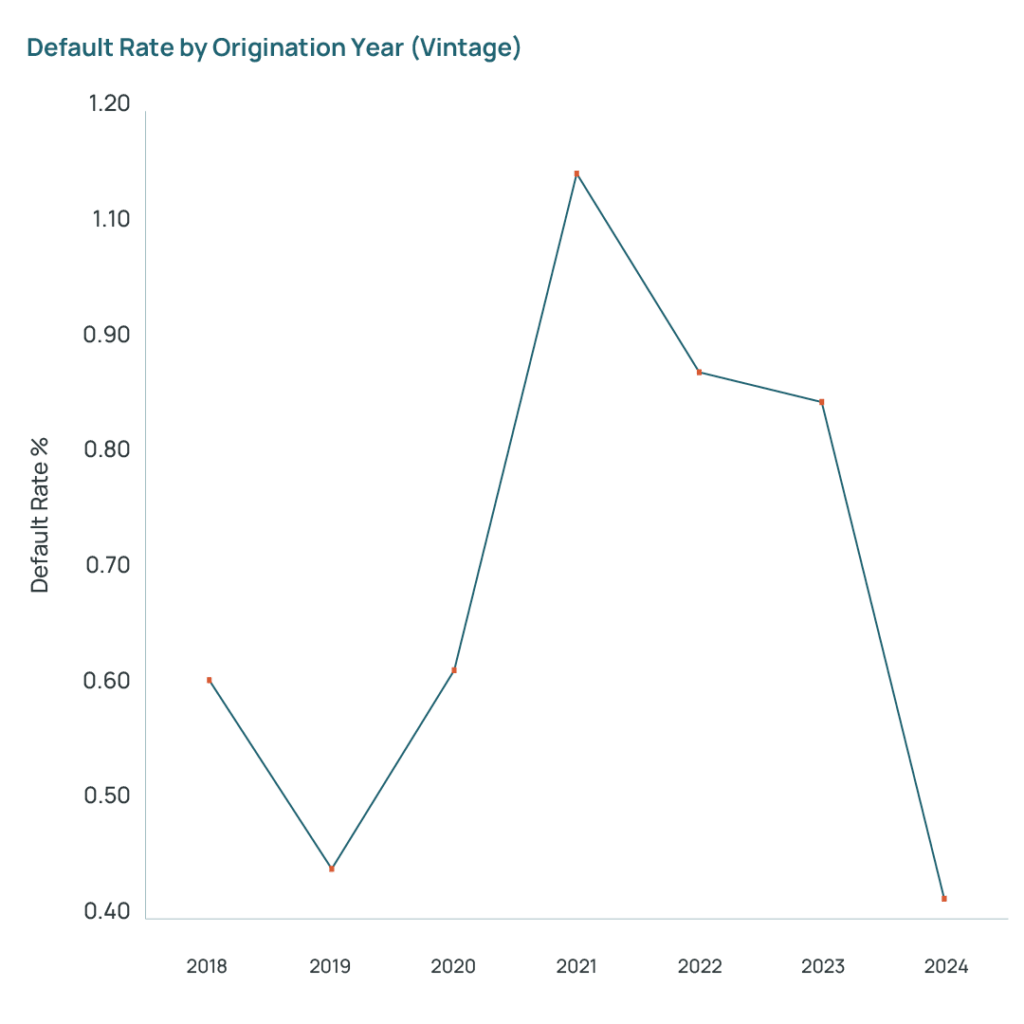
Financial institutions need to be alert to these warning signs and adopt a proactive risk management posture before losses materialize.
Financial institutions should leverage high-quality CECL-compliant loan-level data that captures borrower payment behavior, underlying collateral values, and unique borrower and loan characteristics to discover unrealized, embedded risk in their portfolios. Using CECL-grade data and assumptions also represents an aligned view of credit risk across the organization.
The value of using CECL-grade data is its forecasting power for analyzing correlations between delinquency patterns and key macroeconomic variables.
Granular Portfolio Segmentation
Auto loan portfolios with granular, layered segmentation – rather than relying primarily on delinquency bands and credit scores – lead to more effective risk management.
Applying CECL-based PD models using granular segmentation enables financial institutions to identify loans that are more likely to correlate with future defaults under adverse economic conditions.
Scenario Analysis
Stress testing is an important risk management tool and should be incorporated in active portfolio management.
A CECL-based approach to stress testing reveals portfolio segments exposed to loans with risk factor combinations that exhibit much higher default probabilities in certain recession scenarios.
Data-Driven Strategic Adjustments
Forward-looking analytics inform both portfolio management, underwriting and pricing strategy.
Financial institutions that use consortium or peer loan performance data to benchmark against their own history can validate assumptions and gauge performance against industry peers.
Fully integrated technology platforms that seamlessly combine CECL compliance, multi-scenario stress testing, portfolio analytics, and real-time monitoring in a single auditable framework are essential for effective risk management at scale.
When CECL compliance, stress testing, and portfolio analytics share a common data infrastructure, financial institutions gain insight into embedded risk throughout any portfolio.
Post-COVID structural shifts in the U.S. auto loan market—elevated balances, extended terms, and negative equity, demand forward-looking risk management that anticipates vulnerabilities before losses occur. Granular segmentation that looks at vintage, loan term, payment amount and equity status, combined with integrated CECL and portfolio stress testing gives banks a forward-looking view of risk by revealing how specific collateral layers perform under changing economic conditions.
AlterDomus’ CECL-integrated ALLL+ and Analytics Platforms transform compliance infrastructure into strategic advantage through multi-scenario stress testing and real-time portfolio analytics. Financial institutions that deploy these capabilities will identify emerging risks early and respond with precision in an evolving credit risk landscape.
To learn more about Alter Domus’ integrated risk management solutions, contact [email protected].
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields
Analysis
As the first half of 2026 comes to a close, private markets continue to navigate a complex landscape shaped by shifting macroeconomic conditions, evolving investor priorities, and growing demand for operational efficiency. This review examines the key trends that defined private equity, infrastructure, real estate, and private debt during H1 2026.
Private equity H1 highlights
Elliott Brown
Global Head of Private Equity
Private equity firms started 2026 hoping to accelerate distributions and kick-start fundraising. Six months on, private equity firms are hoping to accelerate distributions and reignite fundraising.
This is not where private equity firms expected to find themselves halfway through another year.
Dealmakers began 2026 in a positive frame of mind. Global deal value hit US$4.5 trillion in 2025, the second-best year on record, according to figures from the London Stock Exchange Group. Inflation had peaked and interest rates were coming down. After years of tepid M&A and false starts, there was every reason for optimism that 2026 would finally be the year that the PE industry shifted back into gear.
But in a pattern that has become all too familiar for GPs, geopolitical shocks and macro-economic disruption put a long-awaited revival on hold. Again.
In February, the release of a new AI tool wiped US$300 billion of the value of software stocks amid fears that AI agents would replace traditional software-as-a-service (SaaS) tools.
The “SaaS-pocalypse” knocked private equity confidence hard.
Software has been a sector favorite for buyout firms, accounting for around 14% of US PE deal value during the last decade, according to Pitchbook. In 2025, almost one in every five dollars GPs invested was in a software company. At the end of March, private equity software valuations were down 8%, according to MSCI figures analyzed by Bain & Co. The drop was less pronounced than in public markets, but enough to sting.
Just a few weeks later, GPs had another macro-economic jolt to deal with, as conflict in the Middle East led to the closure of the Strait of Hormuz, a shipping lane used to transport around a fifth of global oil and natural gas energy supply. The conflict saw a subsequent rise in oil prices of 60%, bringing fears of inflation and interest rate hikes back into the frame.
These market tremors undermined confidence just as dealmakers were beginning to anticipate a recovery, and the succession of disruptive events had a direct impact on exits, distributions and fundraising.
Global exit value dropped to US$96 billion in Q1 2026, 34% down on Q4 2025 and the lowest quarter on record for exits since Q1 2024.
A stuttering exit market meant little improvement to distributions, which remained at near record lows, according to Bain & Co. Distributions as a percentage of NAV currently sit at 13.4 %. This compares to an average of 25% between 2010 and 2025.
Stalled distributions have meant ongoing tepid fundraising. Global PE fundraising fell to US$373 billion in Q1 2026, according to KPMG analysis. On a 12-month rolling basis, this marked the lowest level for fundraising since Q1 2017.
With the “new dawn” for deals and distributions once again deferred, GPs have become highly selective and flexible.
High-quality companies have continued to trade at good prices (according to MSCI analysis, 75% of portfolio companies have exited at premiums to NAV marks), despite macro mayhem.
The businesses that have been sold, however, represent a very select group of companies.
Companies with hard assets that provide essential services are a case in point, and have exited successfully to buyers seeking deals that offer protection against AI disruption. Platinum Equity, for example, sold waste management infrastructure company Urbaser to Blackstone and EQT in a US $6.6 billion deal.
The pool of assets that GPs can be sure will sell in M&A processes, however, is a small one, and firms have had to plough other furrows to sustain distribution flow in the absence of clean exits.
GP-led secondary deals, where managers transfer select assets from existing funds into new vehicles, reached a record US$108 billion in 2025, up from US$77 billion in 2024, according to Coller Capital. Momentum has carried into this year, even though LP scrutiny of continuation vehicle (CV) terms and potential conflicts of interest has intensified.
CVs, the predominant GP-led deal structure, are now a proven liquidity mechanism for private equity firms, and have, on the whole, generated decent returns for LPs too. StepStone research shows that 60 percent of assets moved into CVs between 2020 and 2024 generated gross returns in excess of 3x. Only 28 percent of assets in the wider buyout market did the same. Debt markets have also provided liquidity optionality. In 2025, buyout firms in the US borrowed US$94 billion from loan and bond markets to fund payouts. In the absence of exits, dividend recapitalizations continued to generate distributions through the first half of this year, with a number of sponsors executing recaps through the first half, according to Bloomberg reports.
There is no doubt LPs would prefer to see an increase in “clean” exits via IPO or M&A, but in a choppy market where listings and deal processes can be hostage to market gyrations, some liquidity has been better than none.
After a very challenging first half of the year, there are at least some signs of respite for firms as they move into H2 2026.
The software sell-off has run its course, and software stocks have recovered to roughly the same “pre-SaaS-pocalypse” levels.
Software companies still face some disruption to pricing models and will have to switch from subscription fees based on headcounts to charges linked to usage and outcomes, but in the long-term, AI could actually prove a tailwind for software companies.
For software-focused GPs, this has come as a welcome relief, especially for those that have backed industry-focused software that has integrated years of proprietary data and is very difficult to pull out and replace.
The conflict in Iran has also simmered down. Oil prices have receded to levels seen before the conflict escalated, and inflationary pressures have subsided although risks remain.
So, as the macro-economic picture stabilizes, is this the moment when the “wave” of delayed dealmaking finally manifests? GPs have seen this movie before and won’t be banking on it.
What firms will be focusing on is playing to their strengths, priming prized assets for exit, running hard at select assets where they have genuine conviction, and taking opportunities to execute CVs and dividend recaps to return capital to investors.
Firms that execute well in these areas will stand out from the crowd and continue to deliver. A period of stability that extends beyond a quarter or two, however, will not go amiss.
Private credit H1 highlights
Jessica Mead
Global Head of Private Credit
The first half of 2026 has been challenging for all alternative asset classes, but none more so than private credit.
For more than a decade private credit has enjoyed an almost uninterrupted growth surge. Private credit assets under management (AUM) reached US$3.5 trillion at the end of 2025, growing more than 10-fold in around 15 years.
Rapid asset growth has been matched by strong returns. According to Hamilton Lane private credit has been a stellar performer for private markets, with private credit 10-year annualized time-weighted returns handily outperforming leveraged loans and bonds.
Private credit’s momentum, however, was firmly checked in the first half of 2026 as the industry encountered a series of concurrent challenges. The year began with investors increasingly anxious about the quality of private credit underwriting after the high-profile defaults of auto-sector lender Tricolor and car parts business First Brands. Senior bankers warned that private debt’s exposure to these defaults was a red flag, with more distressed credits likely to emerge the year ahead.
Credit quality fears were exacerbated early in 2026 when US$300 billion was wiped off the value of technology stocks following the release of agentic AI tools with the potential to disrupt software-as-a-service (SaaS) business models.
Given that software accounts for more than a fifth of private credit portfolios, according to JP Morgan (rising to around 40% when including broader tech and business services companies), the software valuation reset hit investor confidence in private credit especially hard.
This dip in confidence manifested most prominently in a surge of redemption requests from investors in private credit business development companies (BDCs), publicly traded investment vehicles that allow institutions and individual investors to invest in private credit assets.
Managers operating some of the biggest private credit BDCs faced huge redemption requests – ranging from 20% to 41% – forcing managers to either sell assets to meet surging redemption requests, or gate funds and cap quarterly redemption requests. According to the FT, wealthy investors put in requests to withdraw more than US$20 billion from the biggest private credit funds in Q1 2026.
More sizeable withdrawal requests are expected in the second quarter too, as fears about AI disruption and portfolio credit quality persist. The persistent negative mood around BDCs has seen the S&P BDC post negative one-year returns of 22.94%.
Faced with multi-billion-dollar redemption requests, doubts around underwriting quality, and exposure to AI disruption, private credit has been under severe pressure so far in 2026.
Constant bleak headlines about the asset class’s prospects, however, have obscured the reality of its resilience. Private credit has undoubtedly frayed at the edges in recent months, but it hasn’t cracked, even though the prevailing narrative around asset class has suggested otherwise.
Trailing twelve-month default rates for direct lending, for example, only registered 1.5% at the end of January, superior to leveraged loans (3.7%) and high yield bonds (2%), according to KBRA. Direct lending implied recovery rates and average loss given defaults also outperformed leveraged loans and bonds. KBRA analysis also highlighted the quality of existing portfolios, with median interest coverage ratios (a measure for how easily borrowers can pay debt interest) improving from 1.5% to 1.6% in Q1 2026.
These datapoints indicated that general assumptions about poor underwriting across all private debt portfolios have been overblown. Pockets of risk and distress have been uncovered in some segments of the market, but on the whole private credit has held up well.
Further evidence for the quality of private credit portfolios has been highlighted (of all places) in the BDC market, where managers have sold loans to meet redemptions without having to swallow discounts to trade the assets.
For example, direct lending assets that were sold by managers to meet redemption requests in early 2026 generally traded at or close to par value, indicating that institutional buyers retained confidence in the underlying quality of the loans. These transactions suggest that concerns about widespread underwriting weakness may be overstated, as sophisticated investors have continued to acquire private credit assets at only modest discounts.
The gap between redemption requests and the liquidity managers are able to unlock to meet those requests is more a reflection of private credit’s inherent illiquidity rather than the underlying credit quality.
Hightower Advisers highlights that unwinding illiquid private loans involves time and cost, leaving managers having to find a delicate balance between meeting redemption requests and maintaining portfolio integrity for existing investors.
There is no value in selling down large portions of portfolios at a low point in the cycle, and the expectation is that managers will move to spread redemptions out over time to balance investor requests for liquidity with taking time to hold assets through a volatile cycle and protect portfolio value.
This could see redemption requests remain a feature of the market for several quarters as they work through the system.
Looking ahead to the rest of the year and into 2027, private credit not nearly as stressed as press coverage has suggested.
Portfolios are holding up impressively in a highly challenging and complex market. Private credit also continues to outshine other fixed income asset classes. Yields to maturity for newly issued direct lending deals are sitting at around 9.3% according to JP Morgan figures, versus 7.7% for syndicated loans and 6.9% for high yield bonds.
Private credit also remains well capitalized. Inflows into publicly traded private credit BDCs are expected to slow as first-half market disruption washes through the system, but institutional appetite for private credit funds is as strong as ever, with first quarter closed-end private credit fundraising reaching a record high of close to US$100 billion, according to Private Debt Investor.
Private credit has had more than its fair share of challenges in 2026, but even through this tough period the asset class has shown that resilience across cycles remains is defining feature.
Real estate H1 highlights

Maximilian Dambax
Global Head of Real Assets
Real estate investors began 2026 in an optimistic mood, expecting to build on momentum from the second half of 2025 when select markets showed encouraging signs of recovery.
The Iran conflict cast a shadow over building optimism, as rising oil prices increased the chances of inflation and interest rate hikes, with potentially negative impacts on property valuations.
Real estate investors and dealmakers, however, have responded to another round of geopolitical dislocation with relative calm.
Direct real estate deal value reached US$216 billion in Q1 2026, up 18% year-on-year, according to JLL figures. Cross-border deal activity accounted for US$55 billion of this total, the best quarter for international real estate transaction volumes since 2022, highlighting the resilience of real estate deal flow.
Real estate fundraising proved more challenging, falling 50% year-on-year in Q1 2026 to US$43.96 billion, according to PERE figures.
First quarter numbers for 2026, however, were up against tough Q1 2025 comparables, when two mega-fundraises by Blackstone and Brookfield alone contributed US$35.5 billion of the Q1 2025 total. When figures are adjusted to take account of these outlier closes, the drop in Q1 2026 fundraising narrows. The first three months of 2026 have also surpassed 2023 and 2024 Q1 totals, signaling an improving market, despite recent macro disruption.
Steady deal activity and relatively stable fundraising, however, do not signal a broad-based real estate rally.
The recovery is real, and the asset class is enjoying more stability after navigating compounding headwinds, including the post-pandemic office vacancies, the ongoing displacement of physical retail by e-commerce, geopolitical tariff pressures, and a persistently elevated interest rate environment.
But the rebound is also uneven, and this is fundamentally changing the way investors and managers generate their returns.
Real estate has come through a benign cycle where low interest rates and sustained capital rate compression boosted returns, UBS notes. These tailwinds have now faded, and in the current cycle, performance will be determined by skilled asset selection, informed underwriting, and operational capability.
In today’s evolving market environment, investors and managers can no longer assume that superior asset quality in a prime location will be sufficient to drive long-term returns.
Successful dealmakers will be the ones who can anticipate whether assets can meet the needs of future tenants and adapt to reconfiguring supply chains that prioritize domestic manufacturing, according to UBS.
The importance of evidencing genuine operational real estate capability is already influencing fundraising trends. Value-add strategies (where managers buy underperforming properties and increase value through renovations and operating improvements) accounted for 56% of capital raised in Q1 2026, more than triple the amount raised by the next largest strategy by value, according to PERE. This represents the highest share of value-add fundraising since 2021.
The importance of operational real estate expertise is further underscored by the effect of AI on the real estate sector, both directly, in areas like digital infrastructure, and indirectly in real estate categories like warehousing, logistics and offices.
The most visible impact of AI on real estate is the construction of data centers to run AI technology. JLL estimates that data center capacity will have to double by 2030 to generate the computing power required to meet AI usage demand. This will require investment of up to US$3 trillion.
The forecast demand for compute capacity has been a key driver of real estate M&A and fundraising, with data center strategies accounting for a quarter of real estate fundraising in Q1 2026, according to PERE.
Investors are deploying capital towards strategies where operational improvement, not asset appreciation or market momentum, is the primary driver of performance, reflecting a recognition that future returns will derive from active management, not market conditions.
Indeed, AI’s influence on real estate extends well beyond data centers.
Office sector investors, for example, have been monitoring the impact of AI on office vacancy rates closely.
If AI does lead to significant productivity gains and headcount reductions, there will be an impact on an office sector that is still adjusting to post-Covid working practices.
According to Moody’s figures reported by Axios, employees in the US are spending around a quarter of their working hours working from home, up from just 7% pre-pandemic. Even though companies have pushed staff to return to the office, office vacancies climbed to a record high of 21% in the US in Q1 2026. AI’s potential impact on the workforce is another factor that is holding back demand for office space, although in some cities demand from AI-led companies is boosting office demand. According to CBRE, AI companies have taken up around 1.5m square feet of traditional office space in central London, most of it since 2022. AI now accounts for more than a third (34%) of technology industry office demand – up from just a 4% share in 2015.
Understanding the impact of AI and changing working patterns on office real estate will demand operational insight, as investors aim to protect portfolios against downside risk, but also take advantage of upside opportunities as office dynamics shift.
An operational lens will be equally essential in logistics and warehousing. Vacancy rates for logistics assets are stabilizing across all regions, according to JLL, and higher value manufacturing, increasing defense spending and ongoing e-commerce growth are all positive drivers of long-term logistics demand. Asset selection will be crucial to tap into these specific growth drivers.
The definition of an attractive asset is being fundamentally redefined by occupier demand. Tenants are no longer evaluating real estate on the basis oflocation alone. Tenants increasingly want to customize sites and are looking for assets that can accommodate future requirements, such as automation and robotics, and have the necessary grid connections to power these technologies. For owners and investors, meeting this evolving occupier mandate will be central to sustaining asset relevance and long-term performance.
Looking ahead to the second half of 2026, the geopolitical picture is improving following progress in negotiations to end the war in Iran. Oil prices have come down as an end to the conflict has come into view, reducing inflationary pressures and improving the interest rate outlook.
These are meaningful and timely developments for a real estate sector that will be aiming to rebuild momentum and confidence after stepping back from deals and investment when the Iran conflict first escalated.
But while a stabilizing macroeconomic backdrop may ease decision-making for real estate dealmakers, it will not determine success in a sector that is still in a phase of long-term structural transformation. Operational expertise and disciplined asset selection, rather than low interest rates and rising asset valuations, are now the main drivers of performance in a sector that has fundamentally changed following the pandemic and will continue to evolve as AI changes the way people work,live, and ultimately consume space.
Infrastructure H1 highlights
Maximilian Dambax
Global Head of Real Assets
In a volatile first half of 2026 infrastructure assets distinguished themselves as a source of resilient performance and a buffer against downside risk in turbulent markets.
Over three, five, and ten-year time horizons private infrastructure has posted gross returns in the 10% to 13% range, outperforming listed infrastructure and global bonds, according to CBRE figures.
The asset class has delivered these mid-teen returns with minimal downside risk. Since 2011, there has not been a single five-year period where private infrastructure has lost money, according to Hamilton Lane.
Investors have taken note and allocated capital accordingly. Private infrastructure fundraising reached an all-time annual high of US$289 billion in 2026, according to Infrastructure Investor.
Fundraising did slow in Q1 2026, coming in at US$26.4 billion, down from US$67.5 billion in Q1 2025 and US$39.2 billion in Q1 2024, but private infrastructure assets under management (AUM) remain close to record highs of US$1.6 trillion, and steady inflows into infrastructure funds are anticipated through the second half of the year.
Soaring demand for computing capacity to power the artificial intelligence (AI) boom remains the single biggest driver of overall infrastructure performance.
Consumption of tokens (the fundamental units of data large language models use to process and generate text) is expected to increase 24-fold by 2030 as use of agentic AI tools, which perform tasks autonomously, ramps up, according to Goldman Sachs.
This will underpin ongoing demand for investment in data centers and associated digital infrastructure, including 5G towers and fiber networks. BlackRock’s base case forecasts predict that data center load capacity will nearly double by 2030 from 2025 levels to meet demand.
Private infrastructure capital is emerging as an essential financing force behind the accelerating build-out of the AI infrastructure, and the sector is unlocking substantial pipelines of data center investment opportunities for managers to pursue.
In the US, for example, private capital investment in data centers has more than tripled from previous highs to reach US$45.70 billion, and now accounts for 72% of overall US data center investment, according to S&P.
The AI buildout is also spurring investment in power and electricity infrastructure. Data centers require large amounts of power to run and electricity demand from AI-focused data centers climbed by 50% in 2025, according to the International Energy Agency (IEA).
Advances in AI data center architecture and chip technology have delivered significant gains in AI energy efficiency, but this has been offset by ever more sophisticated – and energy consumptive – AI applications. The IEA forecasts that this will see data center electricity demand double between 2025 and 2030, reaching 950 TWh.
Data center buildouts are not the only factor driving up demand for electricity. Advanced manufacturing, the accelerating adoption of electric vehicles and climate-controlled systems are also pushing up electricity consumption.
This is not only driving up demand for power generation capacity, but also for grid investment. The IEA estimates that annual grid investment will have to increase by 50% by 2030 to meet forecast electricity demand.
Geopolitical conflict and energy security concerns are also contributing to investment opportunities in energy infrastructure. Countries importing hydrocarbons are home to around 70% of the global population, according to BlackRock, and are boosting investment into assets that diversify the energy mix and secure “home-grown” supply, such as renewables and nuclear.
Momentum behind private infrastructure fundraising and dealmaking is building, but the asset class also faces challenges.
As has been the case across all private markets asset classes, liquidity bottlenecks have disrupted the cadence and volume of distributions to private infrastructure investors. Infrastructure investments do typically have longer investment timelines than other alternative assets, such as buyouts and growth capital, but even when this is taken into account, private infrastructure hold periods are extending well beyond what investors anticipated.
According to Hamilton Lane, the number of years it takes to liquidate private infrastructure assets came in at around 10 years in 2025, the longest period on record since 2000.
The slow pace of distributions is reconfiguring investor priorities, forcing managers to adapt their strategies to deliver what investors want.
Liquidity is the priority, and investors are favoring infrastructure categories that offer clearer and more credible pathways to liquidity against an uncertain market backdrop.
Mid-market infrastructure has attracted growing investor attention, as smaller assets, are easier to exit in downcycles.
Signs of growth in investor appetite for exposure to infrastructure debt and infrastructure secondaries further underscore the premium placed on liquidity. Fundraising for infrastructure debt nearly doubled from Q1 2025 levels in Q1 2026, according to Infrastructure Investor. Infrastructure secondaries fundraising, meanwhile, used to make a fractional contribution to overall infrastructure fundraising, but now accounts for around 8% of total takings.
The long-term fundamentals underlying the investment case for private infrastructure remain largely intact and compelling, but the strategies investors are implementing to build exposure to the asset class are evolving.
The performance and resilience of private infrastructure through a volatile cycle are changing the way investors view the asset class.
Traditionally positioned as a defensive asset class designed to generate yield, infrastructure is evolving into an allocation that can also generate growth.
Core infrastructure categories, including transport, roads, ports and utilities, continue to give investors stability and predictable cash flows. This stability has been complemented by upside opportunity, as demand for data centers, and the electricity to power them, soars.
In an uncertain world, private infrastructure has become an essential component of a well-constructed institutional portfolio, rather than a niche add-on.
Analysis
Luxembourg has cemented its position as Europe’s premier fund domicile, commanding 42% of worldwide cross-border public market assets. We explore what makes it the jurisdiction of choice and what it takes to make it work for your fund.
Conor O’Callaghan
Director, Client &
Industry Solutions
Bruno Bagnouls
Global Partner Director
For global asset managers, fund domicile is a strategic priority defining long-term growth and institutional credibility. As Europe’s primary gateway for alternative investments, Luxembourg offers a sophisticated regulatory environment that enables managers to scale, secure institutional capital, and build trust through cross-border distribution depth.
Luxembourg remains central to European capital access. On 31 March 2026, Luxembourg undertakings for collective investment held total net assets of EUR 6,207.82bn, according to the Commission de Surveillance du Secteur Financier (CSSF). The same CSSF update recorded 288 authorized investment fund managers as of 30 April 2026.
Industry data from the Association of the Luxembourg Fund Industry (ALFI) also shows the scale of the wider market. Luxembourg-domiciled Alternative Investment Funds (AIFs) account for more than €3.1 trillion, representing a massive expansion in the private market space.
For managers in private equity, venture capital, private debt, real estate, and infrastructure, the advantage of Luxembourg lies in what it simplifies. Beyond initial recognition, success depends on robust governance, reporting, and fund service provider arrangements that manage the complexities of the fund lifecycle.
Luxembourg’s position is built on scale, familiarity, and cross-border distribution. PwC Luxembourg’s 2024 global fund distribution data cited Luxembourg as the first domicile for 72% of the top 51 firms and noted that it handled 52.3% of true cross-border investment funds globally.
The latest ALFI Broadridge cross-border distribution study found that cross-border fund assets reached EUR 8.5 trillion in 2025, with Luxembourg accounting for 42% of worldwide cross-border public market assets..4 For cross-border strategies, broader AIFM services may also be relevant to management, oversight, and reporting needs.
Those figures are significant because institutional investors do not assess domicile in the abstract. They look for structures that their internal teams, consultants, custodians, counsel, and investment committees already understand. Funds domiciled in Luxembourg benefit from that market familiarity.
The benefits of Luxembourg investment funds, therefore, start with recognition. Investors, advisers, administrators, depositaries, auditors, directors, and regulators are familiar with the market’s main fund regimes. That familiarity can reduce friction during fundraising, onboarding, reporting, and ongoing fund operations.
Luxembourg hosts a dense network of administrators, depositaries, auditors, and legal advisers who manage complex operations—from accounting and capital activity to governance and regulatory filings. This ecosystem provides essential regulatory credibility and operational scale for international managers.
The local workforce’s expertise in EU regulatory expectations reduces the need for GPs to build internal teams prematurely. Consequently, Luxembourg-domiciled funds are supported from formation and launch through to reporting and asset exits.
The appeal for alternative managers lies in the range of legal forms and regulatory regimes that can be matched to investor eligibility, asset class, governance needs, and distribution plans. Common options include reserved alternative investment funds, specialized investment funds, investment companies in risk capital, special limited partnerships, and Part II funds. The broader point is straightforward: Luxembourg gives managers several ways to separate the fund vehicle, management company, general partner, and asset holding arrangements.
That flexibility comes with operating demands. A private equity or infrastructure fund may require capital calls, distributions, financial statements, audit support, investor reporting, regulatory filings, board materials, tax data, and document control. These workstreams need clear ownership, agreed timelines, reliable data, and review processes. Limited partners expect accurate reporting, regulators expect evidence of compliance, and boards need materials that support proper oversight. For managers without a local Luxembourg operating team, those requirements can quickly become difficult to manage internally.
This is where third-party support becomes part of the domicile decision. An administrator can help turn the legal structure into an operating model after the fund has been established. Outsourced fund administration services are one example of how managers may support Luxembourg operations without building every function internally. For managers comparing models, the discussion on in house vs third party fund administration is directly relevant.
The phrase “golden passport” is often used informally to describe one of Luxembourg’s main attractions: The ability to use a European framework for managing and marketing funds across the European Union and European Economic Area.
The CSSF explains that the Alternative Investment Fund Managers Directive (AIFMD) provides an Alternative Investment Fund Manager (AIFM) passport allowing an authorized AIFM approved in an EU or European Economic Area member state to manage alternative investment funds in another member state. It also confirms that the AIFM marketing passport may allow an authorized AIFM to market the AIFs it manages to professional investors across the EU and European Economic Area, subject to the relevant AIFMD conditions.
For managers without an in-house European AIFM, a third-party management company, often referred to as a third-party ManCo, can provide the regulated management company platform required to support a Luxembourg fund. This can be relevant where a non-European GP wants to access European professional investors through an established AIFM structure while keeping investment management, governance, risk, and reporting responsibilities clearly allocated.
This also helps explain why so many funds are domiciled in Luxembourg. The jurisdiction combines European Union market access, a deep alternatives service market, and fund regimes that institutional investors and advisers already know. For a non-European GP, that combination can make Luxembourg easier to explain to investment committees than a less familiar domicile.
AIFM services should still be viewed as an operating and regulatory function, not a distribution shortcut. The AIFM sits within a control framework covering risk management, valuation, delegation oversight, reporting, and investor disclosures.
Luxembourg’s strength is not that regulation is light. It is that the regulatory framework is established, widely understood, and supported by a regulator with deep experience in investment funds.
CSSF regulation is a central part of Luxembourg’s credibility with European institutional investors. Under AIFMD Luxembourg requirements, managers and service providers need governance, risk, valuation, reporting, and disclosure processes that can stand up to review.
The framework is also changing. In March 2026, the CSSF confirmed that Luxembourg had adopted the Law of 3 March 2026 to transpose Directive (EU) 2024/927, known as AIFMD II into Luxembourg law. The update introduced additional liquidity management requirements for Luxembourg-domiciled UCITS and, where relevant, authorized AIFMs managing open-ended AIFs, with effect from 16 April 2026.
For closed-end private equity, private debt, real estate, and infrastructure funds, the direct impact will depend on the fund’s structure and redemption terms. The broader lesson applies across strategies: A domicile decision creates ongoing regulatory work. Managers need processes that can absorb rule changes, update documents, collect data, and produce evidence.
At a high level, Luxembourg investment funds often operate under specific fund tax regimes rather than ordinary corporate taxation, though this is not uniform across all vehicles. Guichet.lu explains that subscription tax, known as taxe d’abonnement, applies to negotiable securities issued by undertakings for collective investment, specialized investment funds, reserved alternative investment funds, and family wealth management companies, with quarterly declaration and payment obligations.
PwC’s 2026 summary adds that rates are based on total net assets, generally 0.01% for institutional or monetary funds and 0.05% for others, with some exemptions. While tax is a draw, managers must also evaluate treaty access, withholding tax, VAT, substance requirements, and anti-abuse rules alongside regulatory needs.
Alternative funds often have lives of ten years or more. Infrastructure and real assets structures may run longer. Luxembourg’s State Treasury reports that major rating agencies assign Luxembourg the highest sovereign rating, AAA or equivalent, with stable outlooks. Its latest update lists stable top-tier ratings from Moody’s, S&P Global Ratings, Fitch Ratings, Morningstar, DBRS, and Scope Ratings. For fund managers, this stability supports long-term planning for regulated vehicles, local service relationships, financing arrangements, and investor governance.
Luxembourg’s position inside the European Union also has implications. It gives managers a domicile inside the EU legal and regulatory system, with access to European fund rules and a professional market built around cross-border capital. That is one reason the country is often described as an EU fund hub and a Luxembourg financial hub.
For international GPs, the value of a Luxembourg domicile extends far beyond initial regulatory and distribution advantages. It provides a mature, reliable foundation for the entire fund lifecycle. Successfully managing a European fund platform requires continuous operational rigor—from the complexities of structuring, compliance, and reporting to the nuances of corporate governance and eventual fund wind-down.
Luxembourg’s distinct advantage lies in its comprehensive service ecosystem, where experienced providers act as an extension of the manager’s team. This infrastructure allows GPs to maintain high operational standards and meet evolving regulatory and investor expectations without the burden of building full-scale local operations from scratch.
By leveraging this sophisticated network, managers can focus on their core investment strategy, secure in the knowledge that every stage of the fund’s life—from launch and day-to-day administration to strategic restructuring—is supported by deep, local expertise.
Through its Luxembourg fund services, Alter Domus provides this critical support, ensuring that operational resilience remains a constant throughout the fund’s journey.
Get in touch to learn more about our range of services.
Please complete the form and a member of our team will be in touch with you shortly.
"*" indicates required fields